

Ulga na start ("start-up relief") is a relief for a new Polish sole proprietorship (JDG): for the first 6 full months of business you pay no ZUS social security contributions, only the health contribution, which is at least PLN 432.54 a month in 2026. You qualify if you are starting a business for the first time, or 60 months have passed since you closed the previous one, and you do not work through the business for your former employer. After it come 24 months of preferential ("small") ZUS at PLN 456.18.
Two things are usually misunderstood: people think the relief covers every payment, and they count the six months from the registration date. The health contribution is due from the first month, and a business started on any day other than the 1st gets a few weeks more relief. Below: the conditions, how to count the period, how to notify ZUS, and how much the relief and preferential ZUS save together over 30 months.
When people search for ulga na start
Someone has decided to open a JDG for an online store, Allegro sales or services, and is working out what the first year will cost. They have heard that "you can skip ZUS for half a year" and check: is it true, does it apply to me as a foreigner, how much is ZUS in the first 2 years, and what happens after the relief.
The most important of these questions is "what comes after". The relief itself is short, while the tax form that decides your health contribution is chosen for the whole year.
Who qualifies for ulga na start
An individual running a JDG, or a partner in a civil-law partnership (spółka cywilna), qualifies if both conditions are met at once:
- A first business or a 60-month break. You have never run a business, or at least 60 months have passed since you last closed or suspended one.
- Not for your former employer. You do not perform, for a company where you were employed under an employment contract in the current or previous calendar year, the same work you did as an employee.
Citizenship does not matter: the relief is the same for everyone who legally runs a JDG in Poland. Whether you as a foreigner may open a JDG at all depends on your citizenship and residence title; that is covered in the guide on opening an online store in Poland.
What you skip and what you still pay
On ulga na start you pay no social contributions for yourself: pension, disability and accident insurance, the Labour Fund and the Solidarity Fund. The health contribution is paid every month, exactly as without the relief.
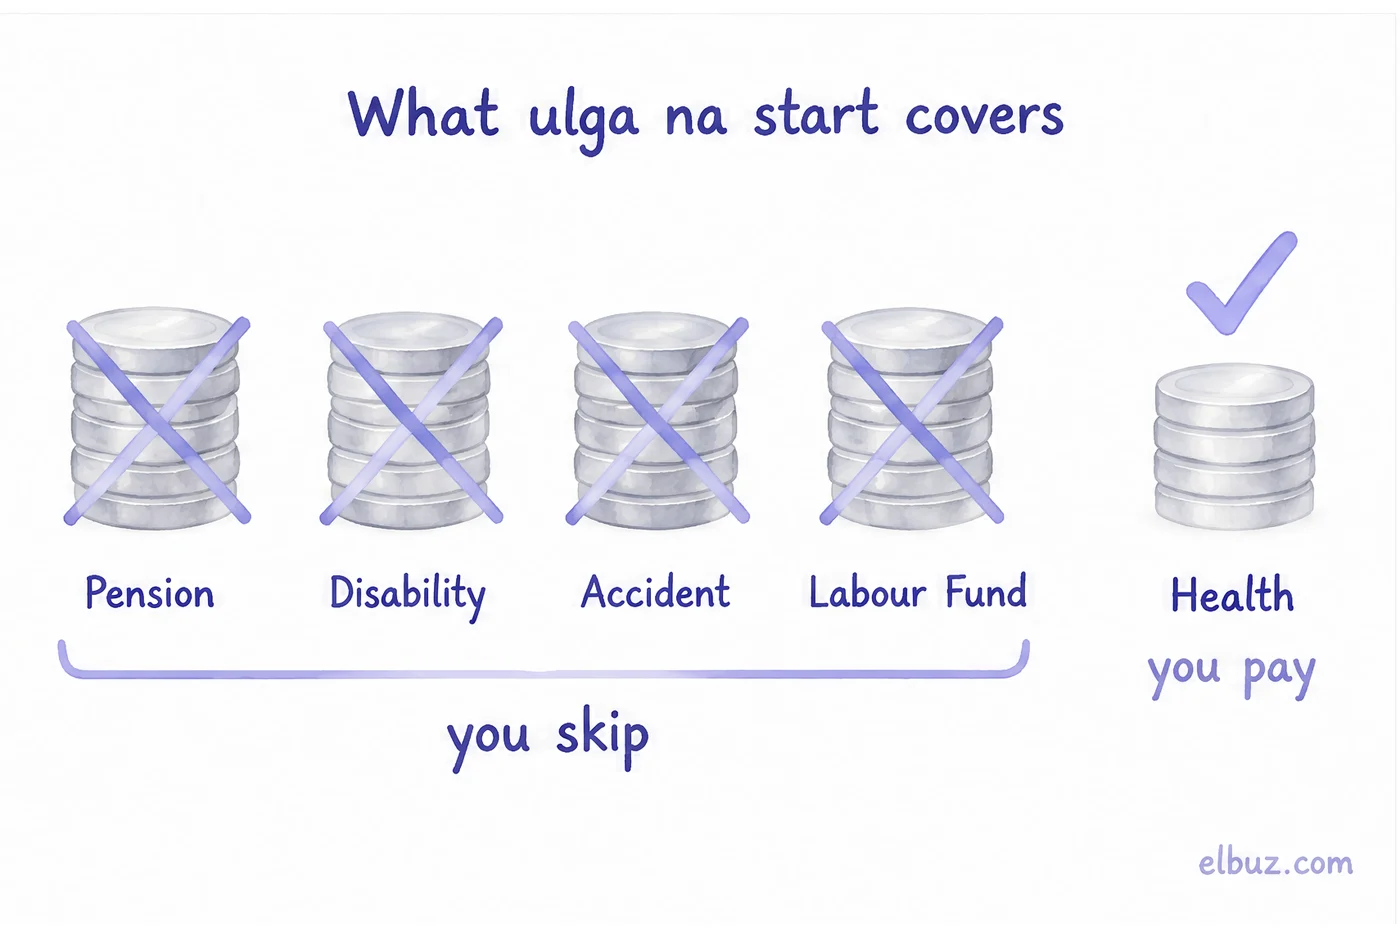
The health contribution depends on your tax form, not on the relief:
| Tax form | Health contribution, PLN | How it is calculated |
|---|---|---|
| Tax scale 12% / 32% | 432.54 | 9% of income, but not less than 9% of PLN 4,806 |
| Flat tax 19% | 432.54 | 4.9% of income, but not less than the minimum |
| Ryczałt, revenue up to PLN 60,000 | 498.35 | fixed amount |
| Ryczałt, PLN 60,000–300,000 | 830.58 | fixed amount |
| Ryczałt, over PLN 300,000 | 1,495.04 | fixed amount |
PLN 432.54 on the tax scale and flat tax is the minimum: with higher income the contribution grows. How the tax forms compare in total is shown in the article on self-employed taxes in Poland.
The price of the relief: while you are on it, nothing goes to your pension account, and sickness, care and maternity benefits from sickness insurance are not available. You keep access to public healthcare, and you can register family members without their own insurance for free (form ZUS ZCNA). The relief applies only to you: for employees and contractors, contributions are paid in full from day one.
How long ulga na start lasts and how to count the 6 months
The relief lasts 6 full calendar months. If the business starts on the 1st of a month, that month counts as one of the six. If it starts on any other day, the incomplete month does not count, and the six months begin with the next one.
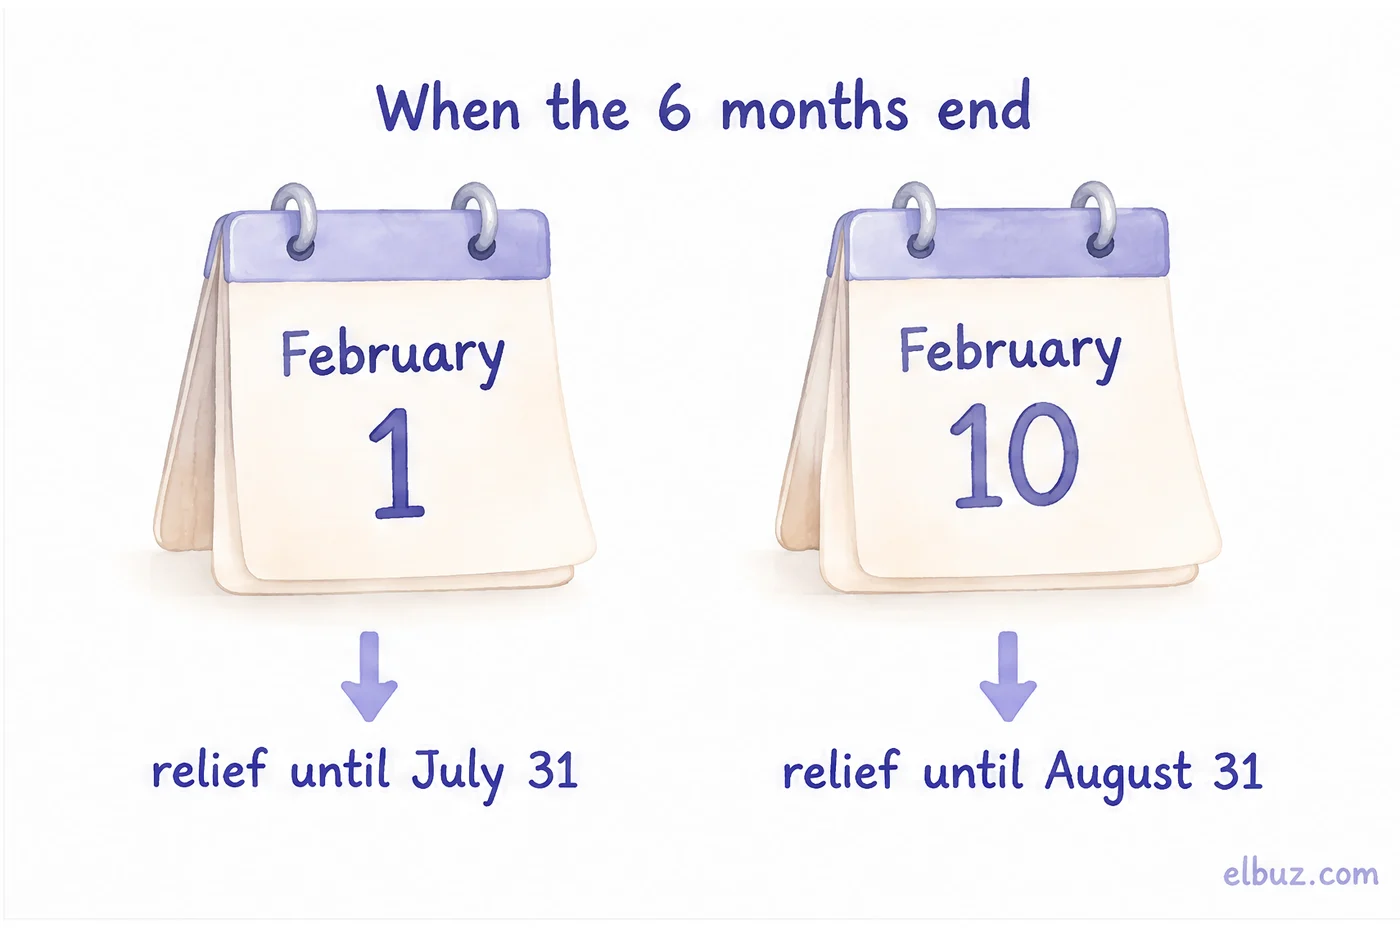
- Business started on February 1, 2026: February is the first month, relief until July 31.
- Business started on February 10, 2026: February does not count, the six months are March to August, relief until August 31. No social contributions are due either for the incomplete February or for the six months after it.
Suspending the business does not stop the clock: months of suspension count towards the six. You can give up the relief at any time before it ends; preferential ZUS then starts on the date you give in the new notification.
How to claim ulga na start at ZUS
There is no separate application: within 7 days of starting the business you register at ZUS for health insurance only, with the code that means ulga na start.
- Register the business in CEIDG. The simplest way is to attach form ZUS ZZA to the CEIDG application; then you do not need to contact ZUS separately.
- Insurance title code 05 40 xx. Without a pension entitlement and without a disability, the code is 05 40 00. The fifth digit: 1 if you receive a retirement pension, 2 if you receive a disability pension. The sixth: 1, 2 or 3 for the degree of disability.
- Family members. If a child or spouse has no health insurance of their own, file ZUS ZCNA; there is no extra contribution for them.
- Every month. File the ZUS DRA declaration and pay the health contribution by the 20th of the following month.
If the business is already registered and you file separately: a paper form is enough if you settle contributions for no more than 5 people; otherwise use the Płatnik program or ePłatnik on PUE/eZUS with a qualified signature or the Trusted Profile.
Preferential ZUS after the relief: 24 months of reduced contributions
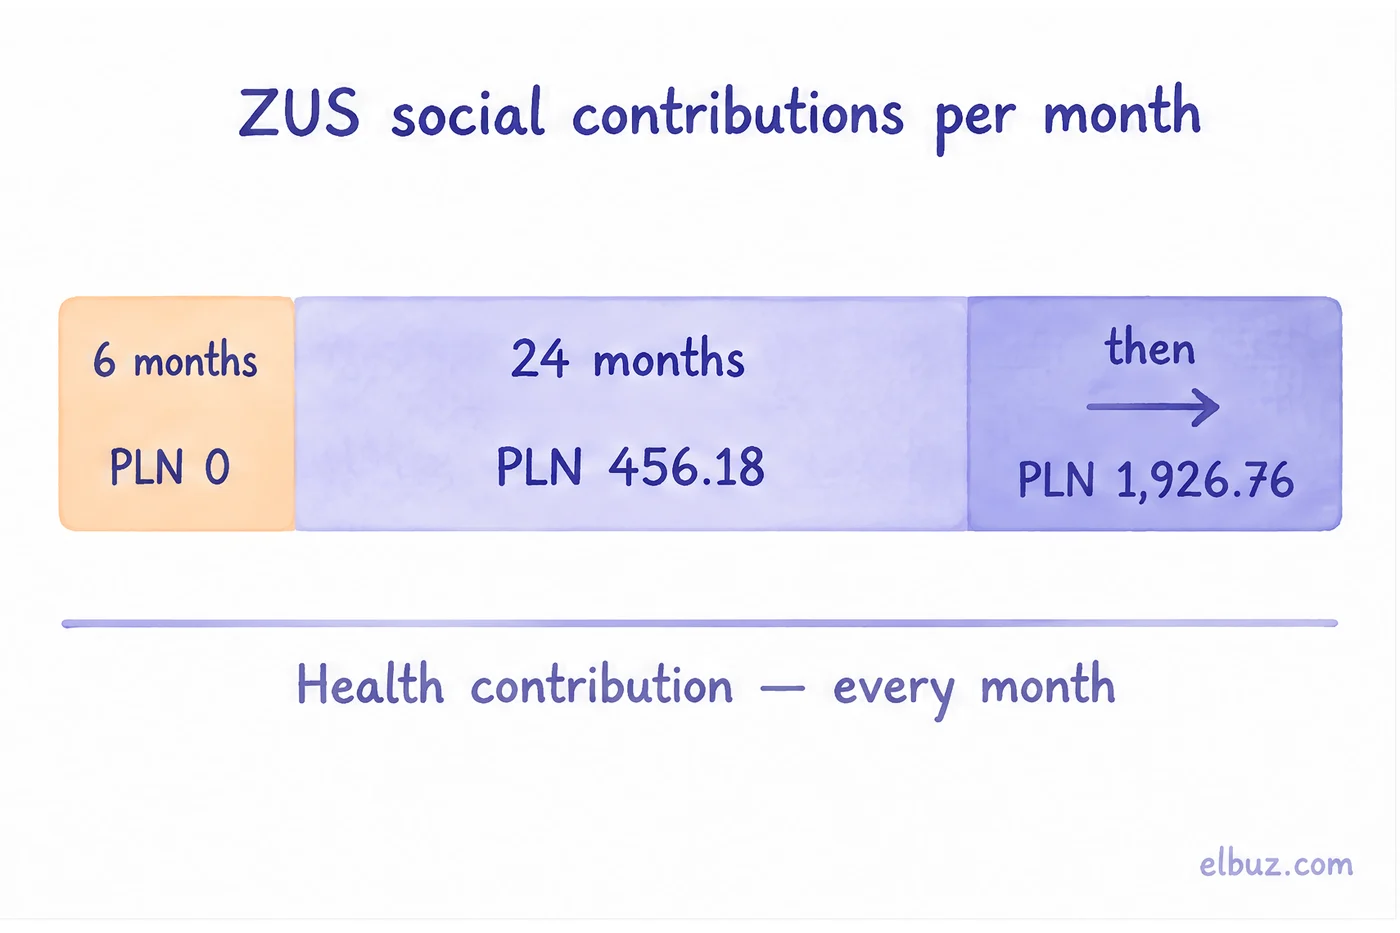
After ulga na start, for the next 24 full months you pay social contributions on a reduced base of 30% of the minimum wage, PLN 1,441.80 in 2026. Contributions are PLN 456.18 a month with voluntary sickness insurance or PLN 420.86 without it. This stage is commonly called "mały ZUS" (small ZUS).
| Contribution | Preferential ZUS, PLN | Full ZUS, PLN |
|---|---|---|
| Contribution base | 1,441.80 | 5,652.00 |
| Pension 19.52% | 281.44 | 1,103.27 |
| Disability 8% | 115.34 | 452.16 |
| Sickness 2.45%, voluntary | 35.32 | 138.47 |
| Accident 1.67% | 24.08 | 94.39 |
| Labour Fund and Solidarity Fund 2.45% | 0 | 138.47 |
| Total | 456.18 | 1,926.76 |
To move to preferential ZUS, file form ZUS ZUA with code 05 70 00 (the last digits differ if you receive a pension or have a disability). The 24 months start the day after ulga na start ends or, if you gave it up earlier, on the date in the notification. Suspending the business does not stop these 24 months either.
After 24 months: full ZUS of PLN 1,926.76, or Mały ZUS Plus if your revenue for the whole previous year did not exceed PLN 120,000. Contributions are then based on income, for at most 36 months in any 60 months of business. Mały ZUS Plus is not available in the first year of a business. The 2027 rates will differ, because the base depends on the minimum wage and the forecast average wage.
How much ulga na start saves: a 30-month calculation
At 2026 rates, ulga na start together with preferential ZUS saves PLN 46,854.48 of social contributions in the first 30 months compared with full ZUS. The relief alone is worth PLN 11,560.56, six months of full contributions you do not pay.
Illustrative example for the arithmetic: 2026 rates are used for all 30 months, although they will change from 2027. Sickness insurance is paid; the health contribution is left out because it is the same in all three options.
- Full ZUS from the first month: 30 × 1,926.76 = PLN 57,802.80.
- No relief, preferential ZUS straight away: 24 × 456.18 + 6 × 1,926.76 = 10,948.32 + 11,560.56 = PLN 22,508.88.
- Ulga na start + preferential ZUS: 6 × 0 + 24 × 456.18 = PLN 10,948.32.
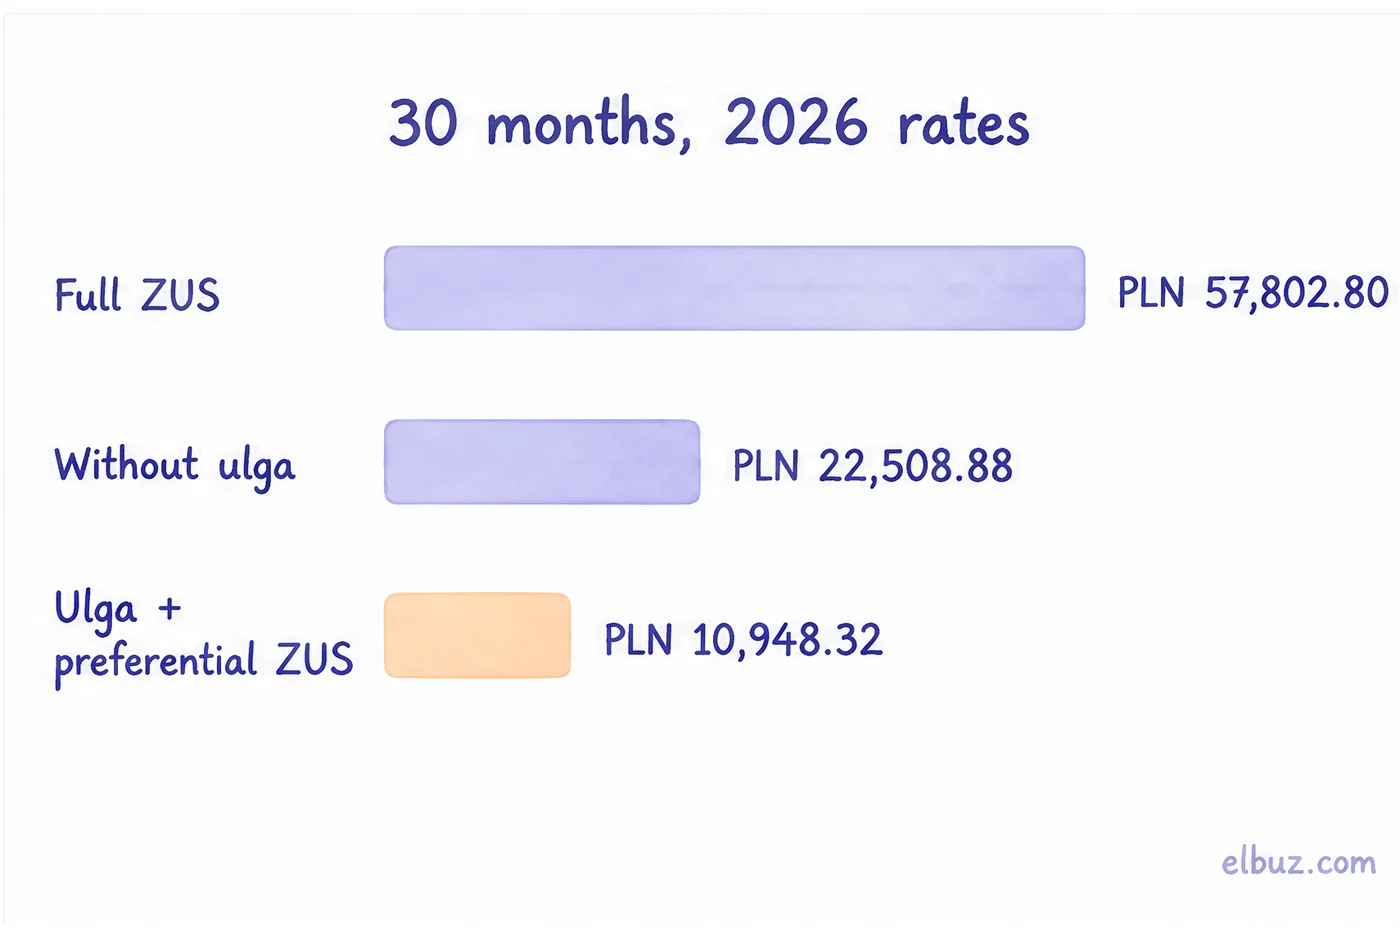
The difference, 57,802.80 − 10,948.32 = PLN 46,854.48, is money that stays in the business at the start. The price is 30 months of minimum pension contributions and half a year without sickness benefit.
When ulga na start does not pay off
The relief almost always pays off, because it costs only half a year of social protection. Giving it up or ending it early makes sense in three situations:
- You are planning a child or medical treatment. There is no sickness insurance on the relief, so no maternity or sickness benefit. Preferential ZUS with voluntary sickness insurance costs PLN 456.18 and gives that protection.
- You will work for your former employer. You are not entitled to the relief; if such work starts during the 24 months of preferential ZUS, the right to it ends on that day.
- You are already insured through an employment contract. Then the obligation to pay social contributions from the JDG may not arise at all, and the relief adds nothing. Check the conditions for this overlap with ZUS before registering. If you are insured in another EU country, the coordination rules decide where you pay; check this with ZUS as well.
If you do not yet know whether the business will take off, you may not need a business at all: unregistered activity lets you sell up to PLN 10,813.50 per quarter in 2026 without ZUS. How to calculate it for a store without a warehouse is in the article on dropshipping and unregistered activity. When the business crosses the VAT threshold is in the guide to VAT registration in Poland.
Frequently asked questions
What is ulga na start?
A relief for a new JDG: 6 full months without ZUS social contributions. The health contribution is still paid every month, at least PLN 432.54 in 2026.
How long does ulga na start last?
Six full calendar months. If the business started on a day other than the 1st, the incomplete month does not count towards the six, so the relief actually lasts longer.
How much is preferential (small) ZUS in 2026?
PLN 456.18 a month with voluntary sickness insurance or PLN 420.86 without it, plus the health contribution. It is paid for 24 months after ulga na start.
How much is ZUS in the first 2 years of business?
For the first 6 months only the health contribution, then 24 months of preferential ZUS at PLN 456.18 plus health. Full ZUS of PLN 1,926.76 starts only after 30 months.
Do I need to apply for ulga na start?
There is no separate application. Within 7 days of starting the business, register at ZUS for health insurance with form ZUS ZZA and code 05 40 00, most simply together with the CEIDG application.
Can foreigners use ulga na start?
Yes. The relief does not depend on citizenship: anyone who legally runs a JDG in Poland and meets the two conditions qualifies.
What is Mały ZUS Plus?
Income-based social contributions available after the preferential period if the previous year's revenue did not exceed PLN 120,000, for at most 36 months in any 60 months of business. It is not available in the first year.
Sources
- Biznes.gov.pl, "Ulga na start – 6 miesięcy bez składek na ubezpieczenie społeczne" (6 months without social contributions): conditions, period, code 05 40, ZUS ZZA, 2026 health contribution — biznes.gov.pl/pl/portal/00285.
- Biznes.gov.pl, "Obniżone składki ZUS przez 24 miesiące" (reduced contributions for 24 months): base PLN 1,441.80, contribution table 456.18 / 1,926.76, code 05 70 — biznes.gov.pl/pl/portal/00286.
- Biznes.gov.pl, "Mały ZUS Plus": PLN 120,000 limit, 36 months in 60, not in the first year — biznes.gov.pl/pl/portal/00284.
- ZUS, social security contribution amounts for 2026: PLN 1,926.76, 1,441.80, 456.18, health PLN 432.54 — zus.pl.
- Biznes.gov.pl, social security contributions of a foreigner running a business in Poland — biznes.gov.pl/en/portal/004112.
Checked on October 31, 2026. The 30-month calculation is an illustrative example at 2026 rates.


