

A Polish sole proprietorship (JDG, jednoosobowa działalność gospodarcza) pays three mandatory things: personal income tax (PIT), ZUS social security contributions and the health contribution. PIT can be paid on the tax scale (12% and 32%), as a 19% flat tax on income, or as ryczałt, a lump-sum tax on revenue, which is 3% for trade. In 2026, full social contributions are PLN 1,926.76 a month and the minimum health contribution is PLN 432.54. VAT comes on top once sales exceed PLN 240,000 a year.
You choose the tax form once a year, and a wrong choice costs thousands: the same business can pay PLN 13,608 or PLN 22,327 a year depending on it. Comparing rates does not help, because 3% and 19% are charged on different bases. Below: each payment with 2026 amounts, all three forms calculated on one illustrative store, and the rule that shows which form is cheaper for you.
When people search for taxes as self-employed in Poland
Usually someone is registering a business in Poland: an online store, Allegro sales, a B2B contract instead of employment. Foreigners who moved to Poland ask the same questions as Poles, only in English: "taxes in Poland for self-employed", "JDG Poland", "income tax Poland", then "ryczałt or flat tax", "how much is ZUS" and "how much is tax-free in Poland".
The usual mistake is comparing rates: 3% looks cheaper than 19%. But ryczałt is charged on revenue and the flat tax on income, so only the totals on your own numbers can be compared.
What taxes a JDG pays and the three forms of income tax
PIT is paid in one of three forms, and the form decides both the rate and the health contribution. The tax card (karta podatkowa) is not available to new businesses.
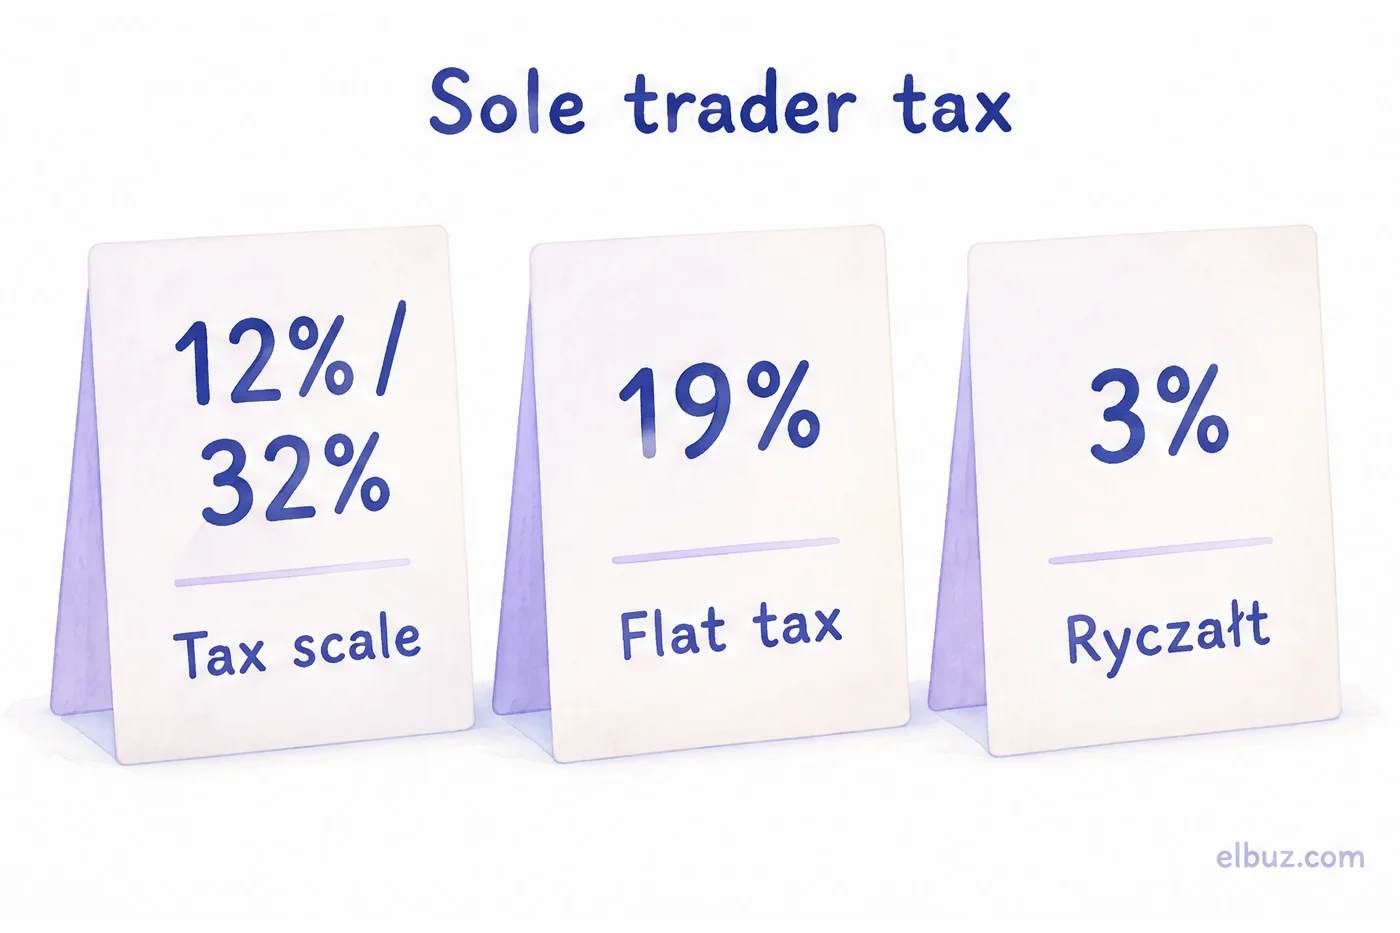
| Feature | Tax scale | Flat tax | Ryczałt |
|---|---|---|---|
| Charged on | Income: revenue minus costs | Income: revenue minus costs | Revenue; costs are not deducted |
| Rate | 12% up to PLN 120,000, 32% above; tax is reduced by PLN 3,600, so the first PLN 30,000 of income is tax-free | 19% on every zloty, no tax-free amount | Depends on the activity: 3% for trade, 8.5–17% for most services |
| Health contribution | 9% of income, at least PLN 432.54 a month | 4.9% of income, at least PLN 432.54; the paid contribution is deductible from income within an annual cap | Fixed by revenue band: PLN 498.35 / 830.58 / 1,495.04 a month; 50% of it is deductible from revenue |
| Suits | Modest income, high costs | Income consistently well above PLN 120,000 | High margin, few costs |
You can choose ryczałt if your 2025 revenue did not exceed €2,000,000 (PLN 8,517,200). The form is changed once a year: a statement by the 20th of the month after the first revenue of the year, through CEIDG or the tax office. Switching from ryczałt to flat tax and back works the same way.
How much ZUS you pay in 2026
A new business owner pays social contributions in three stages: nothing for 6 months, reduced contributions for 24 months, then the full amount. The health contribution is due from the first month, with no relief.
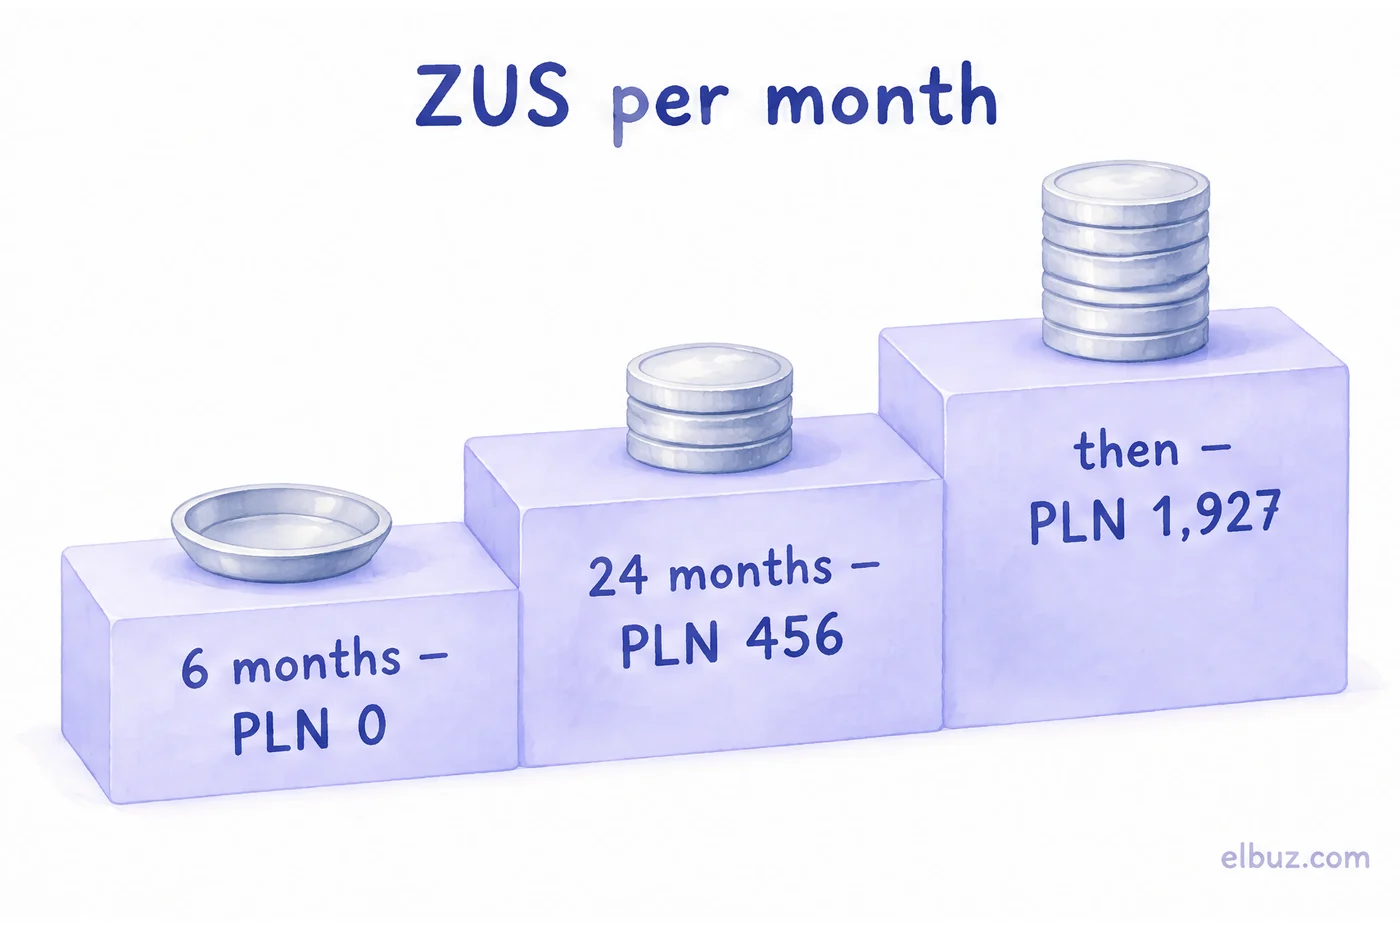
| Stage | Contribution base | Amount, PLN |
|---|---|---|
| Ulga na start, first 6 full months | — | 0 |
| Preferential contributions, next 24 months | PLN 1,441.80 (30% of the PLN 4,806 minimum wage) | 456.18 with voluntary sickness insurance |
| Full contributions | PLN 5,652 (60% of the forecast average wage) | 1,926.76: pension 1,103.27, disability 452.16, sickness 138.47, accident 94.39, Labour Fund 138.47 |
The reliefs apply if you start a business for the first time or 60 months have passed since you closed the previous one, and you do not work through the business for your former employer. After the 24 preferential months, a business with small revenue can move to Mały ZUS Plus. Deadlines and the savings calculation are in the article on ulga na start and preferential ZUS.
Social contributions are deductible: from income on the scale and flat tax, from revenue on ryczałt. ZUS and PIT advances are paid by the 20th of the following month.
How much tax a store pays: three forms on the same numbers
Calculate all three forms on your own numbers and compare the yearly total: PIT + social contributions + health contribution. The formulas:
- Tax scale: base = income − ZUS; PIT = base × 12% − 3,600; health = max(base × 9%, 5,190.48).
- Flat tax: health = max(base × 4.9%, 5,190.48); PIT = (base − health) × 19%.
- Ryczałt 3%: PIT = (revenue − ZUS − 50% of health) × 3%; health by revenue band.
Illustrative example for the arithmetic; the numbers are not market data. An online store in its second year, preferential contributions of PLN 456.18 a month, which is PLN 5,474.16 a year. Revenue PLN 240,000 a year, goods and advertising PLN 180,000, income PLN 60,000. Revenue is above PLN 60,000, so the ryczałt health contribution is PLN 830.58 a month, PLN 9,966.96 a year.
| Line | Tax scale | Flat tax | Ryczałt 3% |
|---|---|---|---|
| Social contributions | 5,474.16 | 5,474.16 | 5,474.16 |
| Health contribution | 5,190.48 | 5,190.48 | 9,966.96 |
| PIT | 2,943.10 | 9,373.72 | 6,886.27 |
| Total | 13,607.74 | 20,038.36 | 22,327.39 |
On the scale and flat tax the health contribution here is the annual minimum of PLN 5,190.48.
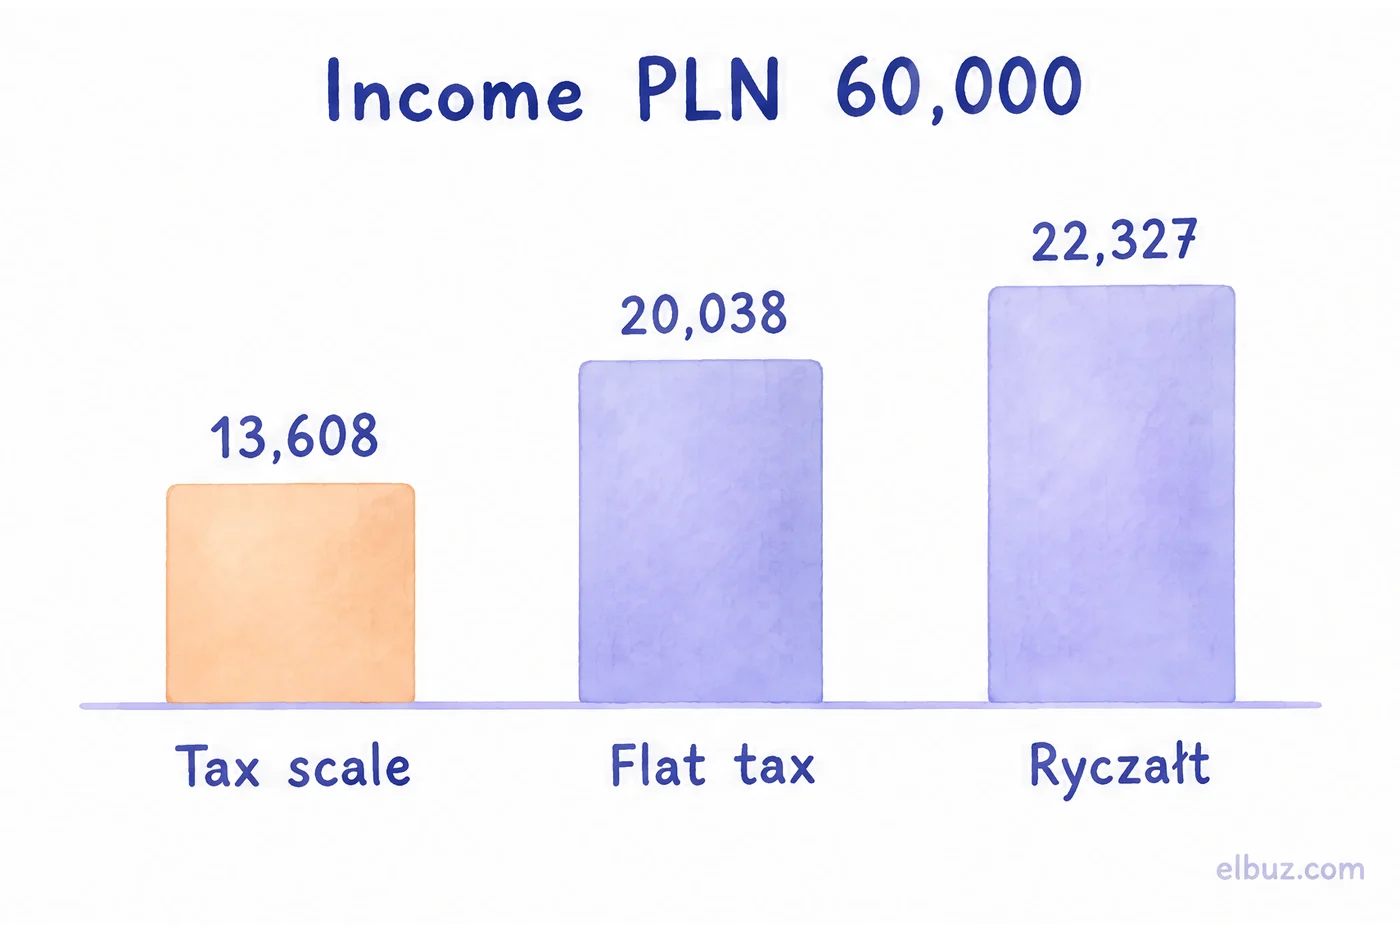
The tax scale is PLN 8,720 cheaper than ryczałt here: PLN 30,000 of income is tax-free, while ryczałt takes 3% of the whole PLN 240,000 of revenue, although only a quarter of it is left as income.
Now the same store with twice the margin: the same PLN 240,000 revenue, costs of PLN 120,000, income PLN 120,000. Ryczałt has not changed, because it is charged on revenue, while the scale and flat tax grew with income:
| Line | Tax scale | Flat tax | Ryczałt 3% |
|---|---|---|---|
| Social contributions | 5,474.16 | 5,474.16 | 5,474.16 |
| Health contribution | 10,307.33 | 5,611.77 | 9,966.96 |
| PIT | 10,143.10 | 20,693.67 | 6,886.27 |
| Total | 25,924.59 | 31,779.60 | 22,327.39 |
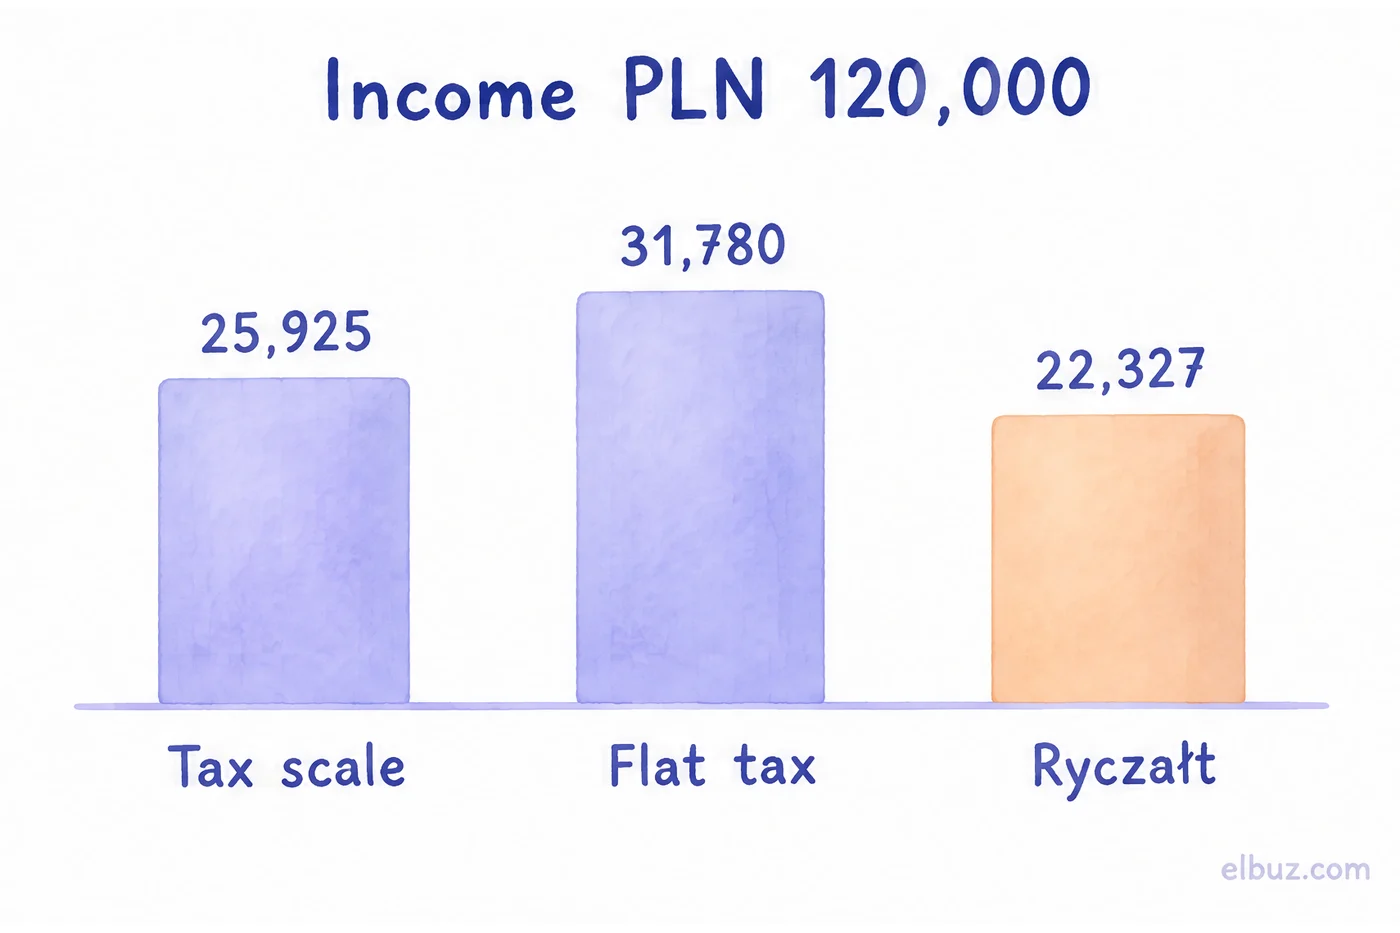
Hence the rule for trade: ryczałt at 3% pays off when costs are a small share of revenue, that is, when the margin is high. Reselling with a 20–30% markup more often comes out cheaper on the tax scale. For a small trading business the flat tax loses to both, because it has no PLN 30,000 tax-free amount; it makes sense when income is consistently well above PLN 120,000, where the scale charges 32%. Calculate your store's margin with the profit margin calculator, then fill in all three columns with your own numbers or ask an accountant to do it.
For B2B contractors selling services the logic is the same, but the ryczałt rate depends on the service code (PKWiU) and is usually much higher than 3%; check your code in the ryczałt rate list before comparing.
When VAT is added to your taxes
When sales in a year exceed PLN 240,000: from January 1, 2026, this is the VAT exemption threshold (previously PLN 200,000). In the first year the threshold is proportional to the days of activity. For some goods there is no exemption from the first zloty, for example electronics and computers sold online. Rates, the VAT-R form and sales to other EU countries are covered in the guide to VAT registration in Poland.
If you are only testing demand, you may not need a business at all: unregistered activity (działalność nierejestrowana) lets you sell up to PLN 10,813.50 of revenue per quarter in 2026 without ZUS, and PIT on that income goes in the annual return. Foreigners can use it if they are allowed to run a business in Poland on the same terms as Poles. How the limit works for dropshipping is in the article on dropshipping in Poland.
How to choose your tax form: step by step
- Plan the year: revenue, goods, advertising, shipping, rent, everything that will be a cost.
- Find the ryczałt rate for your activity by its PKWiU code: 3% for trade, a different rate for services.
- Calculate the three columns with the formulas above, using the ZUS stage you will be in.
- Check the thresholds: PLN 120,000 of income for the scale, PLN 60,000 and PLN 300,000 of revenue for the ryczałt health contribution, PLN 240,000 for VAT.
- Choose the form in CEIDG when you register, or file a statement by the 20th of the month after your first revenue.
Frequently asked questions
What taxes does a sole proprietorship pay in Poland?
PIT on the tax scale, flat tax or ryczałt, ZUS social contributions, the health contribution, and VAT if sales exceed PLN 240,000 a year. After the reliefs end, the minimum is PLN 1,926.76 of social contributions and at least PLN 432.54 of health contribution a month.
Which tax form should I choose in 2026?
The one that gives the lowest total of PIT + ZUS + health contribution on your numbers. In trade with a low margin the tax scale usually wins, with a high margin ryczałt at 3%. See the calculation on the same numbers above.
Is flat tax or ryczałt better?
It depends on the margin. Ryczałt is charged on revenue and pays off when costs are low; flat tax is charged on income and makes sense when income is well above PLN 120,000.
How much is tax-free in Poland?
PLN 30,000 of income a year, but only on the tax scale: the 12% tax is reduced by PLN 3,600. Flat tax and ryczałt have no tax-free amount.
How much is the health contribution in 2026?
9% of income on the tax scale and 4.9% on flat tax, in both cases at least PLN 432.54 a month. On ryczałt it is fixed: PLN 498.35, 830.58 or 1,495.04 depending on annual revenue.
Can a foreigner open a JDG in Poland?
EU and EEA citizens can, on the same terms as Poles; citizens of other countries can if they hold a residence title that allows it, such as a permanent residence permit or an EU long-term resident permit. The steps are in the guide on opening an online store in Poland.
Sources
- Podatki.gov.pl, "Stawki i limity" (rates and limits, updated December 15, 2025): scale 12% / 32%, PLN 3,600, flat tax 19%, ryczałt rates, €2,000,000 limit — podatki.gov.pl.
- Podatki.gov.pl, deduction of health contributions in PIT (updated June 24, 2026) — podatki.gov.pl.
- Biznes.gov.pl, health contribution amounts: PLN 432.54, 4.9%, ryczałt amounts for 2026 — biznes.gov.pl/pl/portal/001052.
- Biznes.gov.pl, social contributions of a business owner: PLN 5,652 base and 2026 contributions — biznes.gov.pl/pl/portal/00274; ulga na start — 00285; preferential contributions — 00286.
- Biznes.gov.pl, choosing the income tax form and the deadline to change it — biznes.gov.pl/pl/portal/00172.
- VAT threshold PLN 240,000 — biznes.gov.pl/pl/portal/00246; unregistered activity PLN 10,813.50 per quarter — biznes.gov.pl/pl/portal/00115.
- Biznes.gov.pl, what types of business activities foreign nationals can conduct in Poland — biznes.gov.pl/en/portal/004055; non-registered activity — 004051.
Checked on October 31, 2026. The store calculations are illustrative examples.


