

VAT registration in Poland means filing the VAT-R form with the head of your tax office before your first sale subject to VAT. It is free and done online: together with the sole proprietorship application in CEIDG, or through e-Urząd Skarbowy. It becomes mandatory once your sales in a year exceed PLN 240,000 (the threshold since January 1, 2026; previously PLN 200,000). Regardless of turnover, you need VAT to sell cosmetics or electronics online, and a business without a seat in Poland must register before its first taxable sale there.
Online stores usually go wrong in two places: they count the full annual threshold although they started mid-year, and they do not know that buying Google or Meta ads requires an EU VAT registration even without active VAT status. Foreign sellers add a third: they assume the PLN 240,000 exemption applies to them. Below: when VAT is mandatory, the first-year calculation, whether voluntary VAT pays off, registration step by step, the rules for sellers without a Polish company, the EU VAT number and the OSS threshold.
When people search for VAT registration in Poland
Usually someone is opening a sole proprietorship in Poland, already sells through an online store or on Allegro, or runs a company abroad and wants to sell to Polish customers, and a wholesaler, marketplace or customer asks for a VAT number. The first searches are "VAT registration Poland" and "Poland VAT number", then "what is a NIP number in Poland", "VAT threshold Poland", "how high is VAT in Poland" and "how to check a Polish VAT number".
"Should I register voluntarily" is usually asked too early. First check whether VAT is mandatory for you from the very first sale: for some goods sold online, and for every business without a seat in Poland, the threshold does not apply at all.
When VAT registration in Poland is mandatory
The small-business VAT exemption does not apply in five situations typical for online trade.
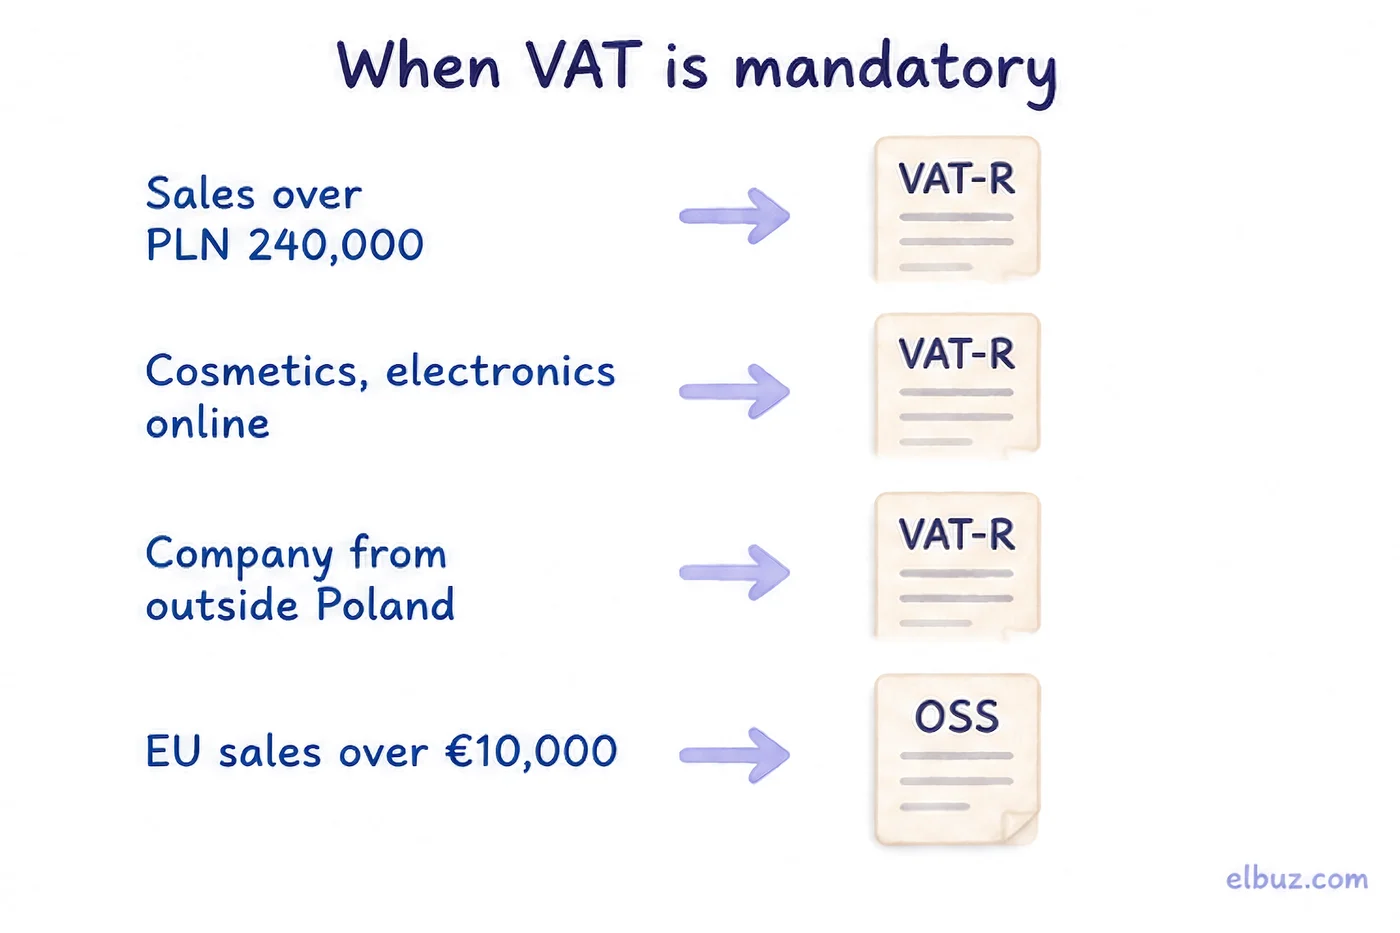
| Situation | What to do |
|---|---|
| Sales in the year exceeded PLN 240,000 excluding VAT | File VAT-R; the exemption ends with the sale that crossed the threshold |
| You sell cosmetics and toiletries, computers and electronics, electrical equipment, machinery online | VAT-R before the first sale, regardless of turnover |
| You sell car and motorcycle parts and accessories, excise goods, precious metal products | VAT-R before the first sale |
| The business has no seat of economic activity in Poland | VAT-R before the first taxable sale in Poland; the exemption does not apply |
| Sales to consumers in other EU countries exceeded €10,000 in the year | VAT of the buyer's country, most conveniently through OSS |
Legal, advisory, jewellery and debt collection services are also subject to VAT regardless of turnover. An ordinary store selling clothing, footwear or homeware uses the general threshold.
The PLN 240,000 threshold in your first year: how to calculate it
If the business started during the year, the threshold is proportional to the period of activity, not the full PLN 240,000. The law says "in proportion to the period", so you can count in days.
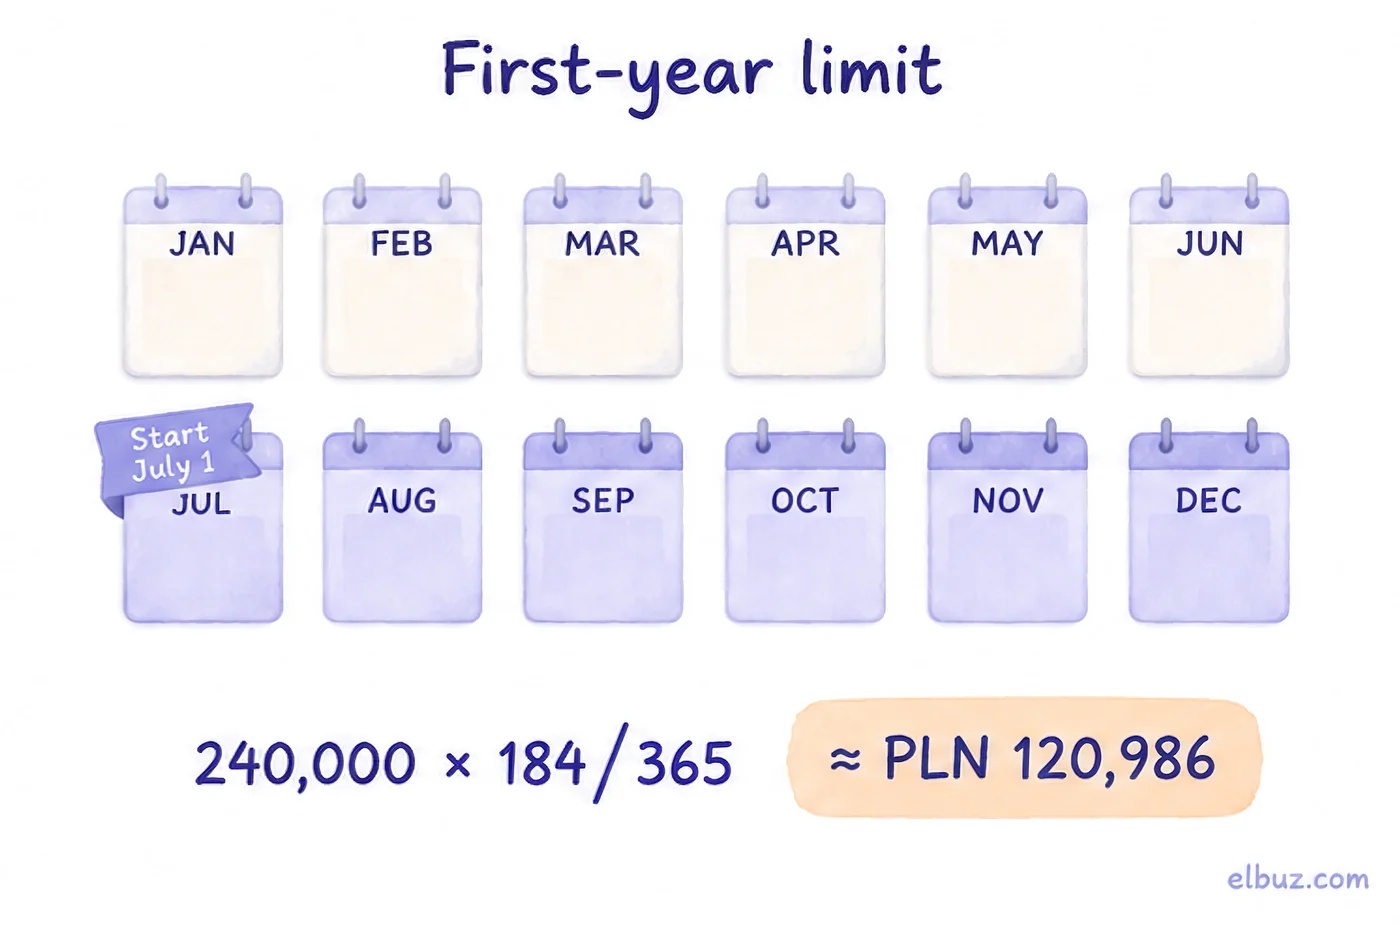
Illustrative example. A sole proprietorship starts on July 1, 2026, leaving 184 days in the year. Threshold: 240,000 × 184 ÷ 365 ≈ PLN 120,986. If sales exceed this amount by December, you charge VAT from the sale that crossed the limit, and VAT-R must be filed before it. When sales get close, confirm the calculation with your tax office.
Sales to consumers in other EU countries that are taxed there, that is, after the €10,000 threshold is exceeded, do not count towards the Polish threshold.
Does voluntary VAT registration pay off for an online store?
When you sell to consumers, voluntary VAT usually reduces what you keep from each sale; when you sell to businesses, it does not. A consumer cannot deduct VAT, so the gross price stays the same and the tax comes out of your margin. A business deducts VAT, so you can add it on top of the price.
Illustrative example for the arithmetic; the numbers are not market prices. A product costs PLN 60 net + PLN 13.80 VAT = PLN 73.80 from the wholesaler. The consumer pays PLN 123 in the store.
| Line | VAT-exempt, PLN | Active VAT payer, PLN |
|---|---|---|
| Price paid by the consumer | 123.00 | 123.00 |
| Purchase from the wholesaler | −73.80 | −73.80 |
| VAT payable: 23.00 − 13.80 | 0.00 | −9.20 |
| You keep | 49.20 | 40.00 |
The same sale to a business looks different: an active VAT payer invoices PLN 100 net + PLN 23 VAT, the business deducts the VAT, and you keep PLN 40 net, just like competitors with VAT. Voluntary VAT therefore pays off mainly when businesses buy from you, when you invest a lot and want to deduct VAT on purchases, or when a wholesaler or marketplace requires active VAT status. Convert net and gross prices with the VAT calculator.
How to register for VAT in Poland: 4 steps
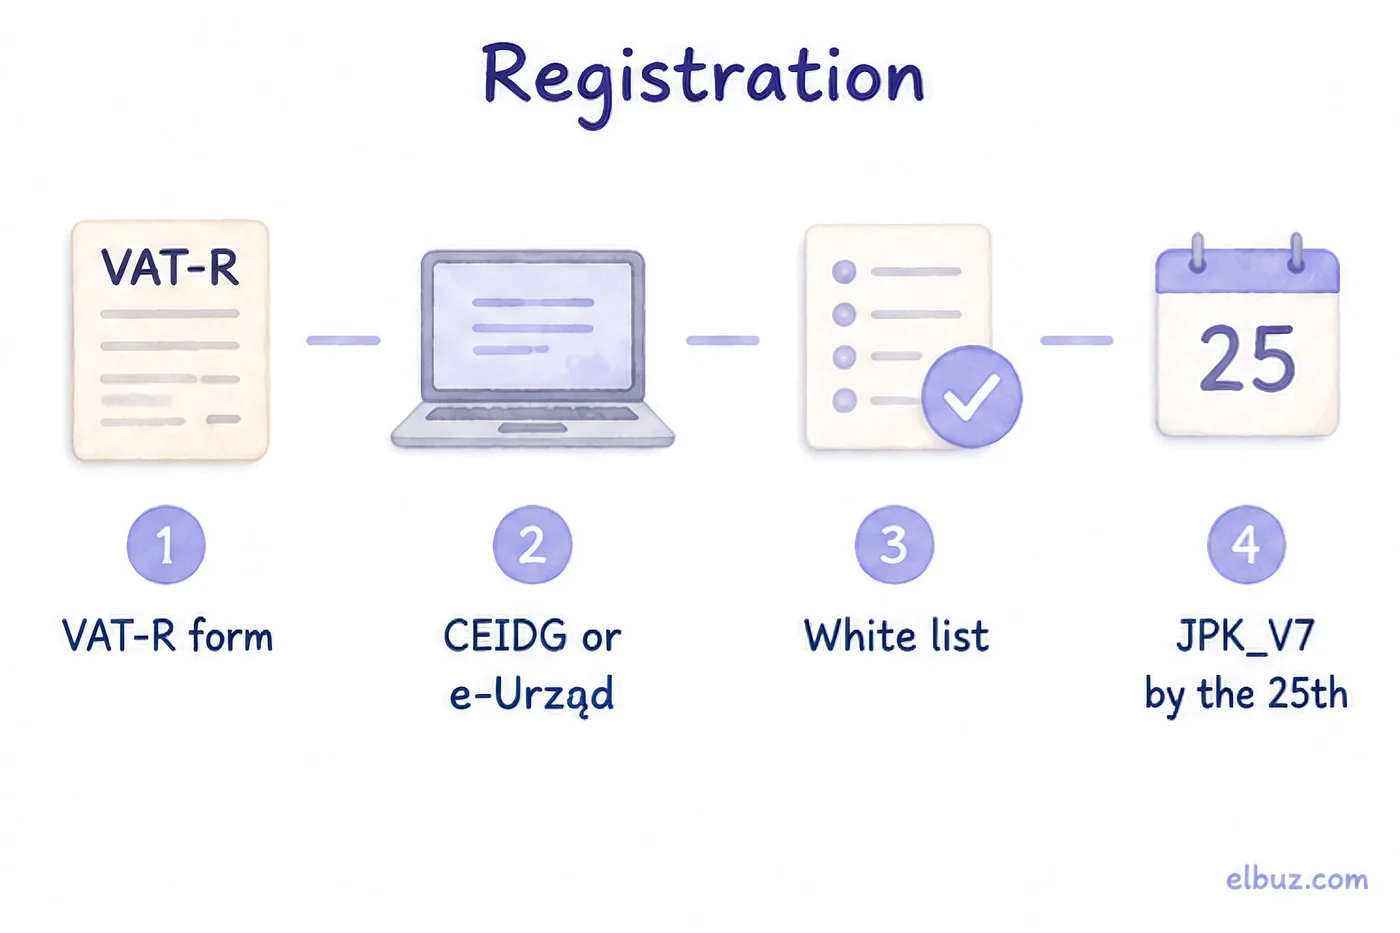
- Fill in VAT-R. In the form you choose your status: "active VAT payer" or "exempt VAT payer" (for the latter, registration is voluntary). File it before the first sale on which you will charge VAT.
- File it online. A new sole proprietorship attaches it to the CEIDG application on biznes.gov.pl, signed with the Trusted Profile (Profil Zaufany). An existing business files through e-Urząd Skarbowy. Filing is free; written confirmation of registration is optional and costs PLN 170 in stamp duty.
- Check yourself on the white list. After registration the business appears in the register of VAT taxpayers (the "white list", Wykaz podatników VAT), where you and your customers can see your status. You check whether a supplier is an active VAT payer the same way.
- File monthly. An active VAT payer files JPK_V7M by the 25th of the following month. Quarterly JPK_V7K is available to small taxpayers (sales up to €2 million a year), but not in the first 12 months after registration.
Poland has no separate "VAT number": your Polish VAT number is your NIP (10 digits). In transactions with businesses in other EU countries it is preceded by the PL prefix, but that also requires EU VAT registration (VAT-UE).
Late VAT-R. Filing late does not cancel the tax: VAT is due from the sale that crossed the threshold even if VAT-R has not been filed yet. If you missed the deadline, file at once and agree with your accountant or the tax office how to settle the VAT due.
Selling to Poland without a Polish company
A business without a seat of economic activity in Poland cannot use the turnover exemption, so it registers as a VAT payer before its first taxable sale in Poland. A seller from outside the EU must, as a rule, also appoint a tax representative (przedstawiciel podatkowy): a Polish entity authorised to keep accounts or provide tax advice, under Article 18a of the VAT Act. The exception is a seller from a country with which Poland has a legal basis for mutual assistance in tax matters; check this for your country with the tax office.
Two situations often do not require Polish registration at all:
- An EU seller shipping to Polish consumers from its home country. Below the €10,000 EU-wide threshold it charges its own country's VAT; above it, Polish VAT is declared through OSS in its home country.
- Goods already in an EU warehouse sold to consumers through a marketplace by a non-EU seller. The VAT Act treats the marketplace as the seller of those goods, and the marketplace pays the VAT on that sale. What remains your obligation, for example when the goods are brought into the warehouse, is worth confirming with a tax adviser.
If you plan regular sales from stock in Poland, a Polish sole proprietorship or company is often the simpler route; the options are in the guide on opening an online store in Poland.
EU VAT number: when you need it even without active VAT status
VAT-UE is a separate registration for transactions with businesses in other EU countries, and an online store may need it sooner than ordinary VAT. A VAT-exempt business must also register for VAT-UE if it buys services from a foreign company, such as Google or Meta advertising, because it settles VAT on that service itself (import of services). An exempt business also needs VAT-UE once its purchases of goods from other EU countries exceed PLN 50,000 in a year.
Registering for VAT-UE does not take away the VAT exemption. An active VAT payer registers for VAT-UE before the first purchase or sale of goods with businesses in other EU countries.
OSS: sales to other EU countries over €10,000
As long as sales to consumers in all other EU countries together stay at or below €10,000 in the current and previous year, you charge Polish VAT. From the sale that crosses the threshold, the VAT of the buyer's country applies. To avoid registering in every country, a seller based in Poland files one return through OSS (the Union scheme).
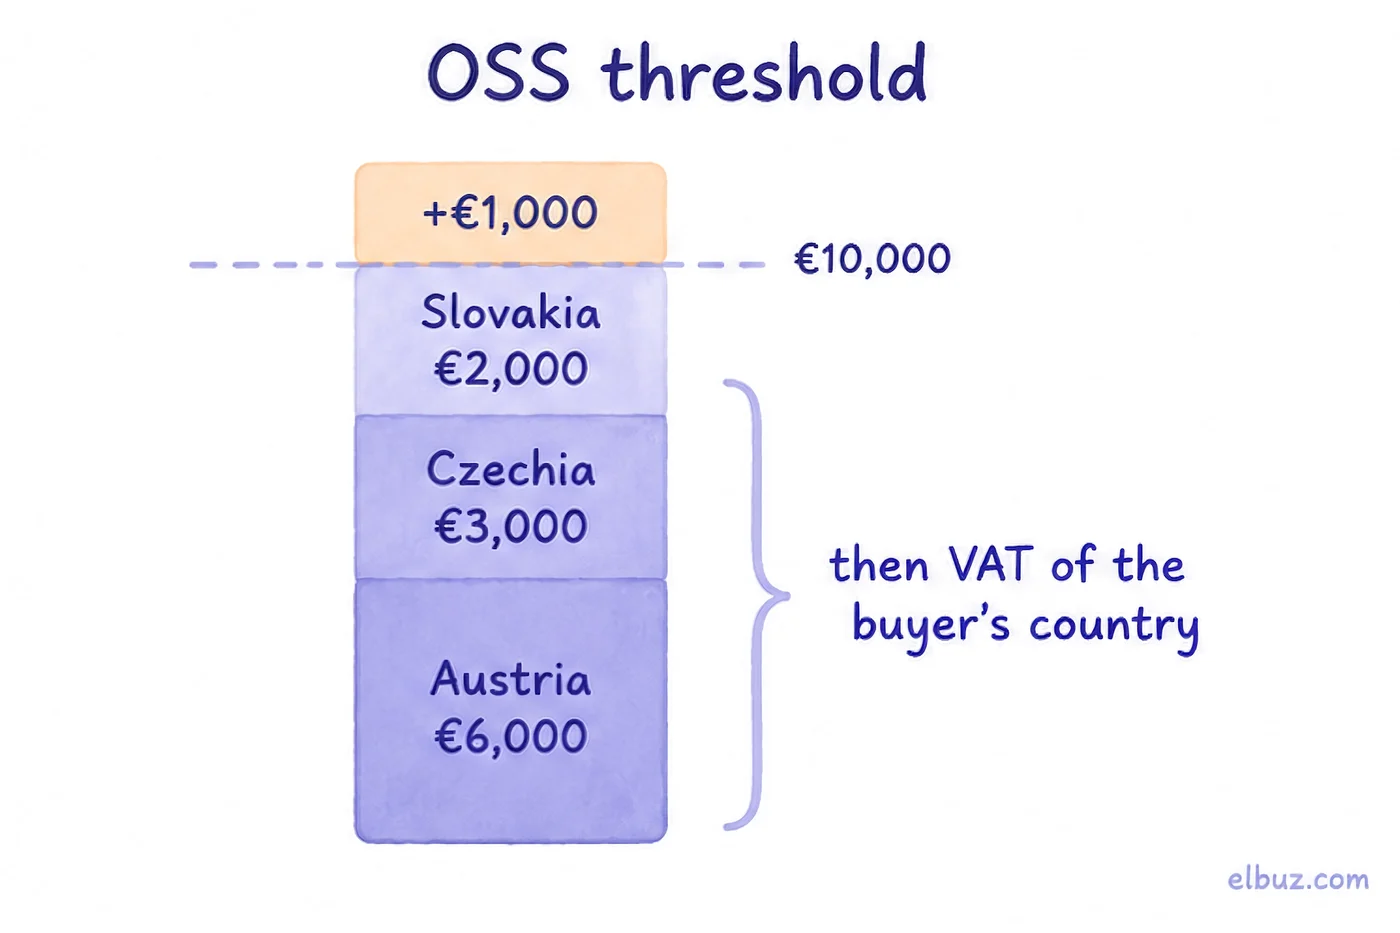
Illustrative example. During the year a store sells €6,000 to customers in Austria, €3,000 in Czechia and €2,000 in Slovakia. Total €11,000: the threshold is exceeded by €1,000, and from that point each sale is taxed at the rate of the buyer's country. The threshold is counted for all countries together, not for each one separately.
- OSS registration: form VIU-R through e-Deklaracje.
- OSS return: VIU-DO quarterly, by the end of the month following the quarter.
- IOSS: for goods shipped from outside the EU in parcels up to €150: registration VII-R, return VII-DO monthly by the end of the following month.
VAT rates and KSeF in 2026
The standard VAT rate in Poland is 23%, the reduced rates are 8% and 5%, and intra-EU supplies of goods to businesses and exports are 0%. You find the rate for your product in the annexes to the VAT Act or on podatki.gov.pl.
Since 2026, invoices are issued in KSeF: from February 1 by businesses with 2024 sales over PLN 200 million, from April 1 by everyone else. Until December 31, 2026, small businesses may issue invoices outside KSeF while their monthly total including VAT stays at or below PLN 10,000. Details and an example are in the article on how KSeF works. If your orders and sales documents are kept in Elbuz, invoices go to KSeF straight from the document; how orders and documents work together is on the order management page.
Common VAT registration mistakes
- Counting the full threshold in the first year. A July start gives about PLN 120,986, not PLN 240,000. The result is back VAT to pay.
- Selling electronics or cosmetics online without VAT. For these goods the threshold does not apply; VAT is needed from the first sale.
- Assuming a foreign company can use the PLN 240,000 exemption. Without a seat in Poland it registers before the first taxable sale.
- Buying Google ads without VAT-UE. A VAT-exempt business must also register for VAT-UE and settle VAT on that service.
- Counting the €10,000 threshold per country. It is one threshold for all EU countries together.
- Registering voluntarily while selling only to consumers. Without large purchases with VAT, the tax comes out of your margin; calculate it before filing VAT-R.
If you are only starting out with a no-warehouse model, the thresholds for unregistered activity are covered in the article on dropshipping in Poland.
Frequently asked questions
What is the VAT threshold in Poland?
PLN 240,000 of sales excluding VAT in a year (from 2026). If the business started during the year, the threshold is proportional to the period of activity; for cosmetics or electronics sold online, and for businesses without a seat in Poland, there is no threshold.
How much does VAT registration in Poland cost?
Nothing: filing VAT-R is free. Written confirmation of registration is optional and costs PLN 170 in stamp duty.
What is a NIP number in Poland?
The Polish tax identification number, 10 digits. It is also your Polish VAT number; for transactions with EU businesses it is written with the PL prefix, such as PL1234567890.
How high is VAT in Poland?
The standard rate is 23%, with reduced rates of 8% and 5%. Intra-EU supplies of goods to businesses and exports are taxed at 0%.
How can I check a Polish VAT number?
In the Ministry of Finance register of VAT taxpayers (the white list), by NIP. An EU VAT number from any EU country is checked in the VIES system.
Do foreign companies need a tax representative in Poland?
A seller from outside the EU that registers for Polish VAT must, as a rule, appoint a tax representative, unless its country has a mutual tax assistance arrangement with Poland. An EU company does not need one.
Is voluntary VAT registration worth it?
It depends on your customers. When you sell to consumers, voluntary VAT usually reduces your earnings because the tax comes out of the margin; when you sell to businesses and buy a lot with VAT, it can pay off.
Sources
- Polish VAT Act (Ustawa o podatku od towarów i usług), consolidated text Dz.U. 2026 item 1263: Art. 18a (tax representative), Art. 22a (€10,000), Arts. 96–97 (VAT-R, VAT-UE), Art. 99 (JPK), Art. 113 (PLN 240,000) — isap.sejm.gov.pl.
- Podatki.gov.pl, VAT rates and thresholds — podatki.gov.pl; VAT forms (VAT-R, VIU-R, VIU-DO, VII-R, VII-DO) — podatki.gov.pl.
- Biznes.gov.pl, VAT registration — ou1609; VAT-UE registration — ou305.
- KSeF, deadlines — ksef.podatki.gov.pl.
- Register of VAT taxpayers (white list) — wykazpodatnikowvat.mf.gov.pl.
- European Commission, VIES VAT number validation — ec.europa.eu.
- European Commission, One-Stop-Shop — vat-one-stop-shop.ec.europa.eu.
Checked on October 31, 2026. The first-year, margin and OSS examples are illustrative.


