

How you close a business in Poland depends on its legal form. A sole proprietorship (JDG) is closed with a free application for removal from CEIDG, and the entry disappears the next business day. A limited liability company (sp. z o.o.) goes through liquidation in the National Court Register (KRS): a resolution before a notary, a notice to creditors in the Court and Economic Monitor (MSiG), distribution of assets no earlier than 6 months later, then removal from the register. Official fees start at PLN 610. If the business can no longer pay its debts, liquidation is not an option: a bankruptcy petition is needed.
Most of the money is lost not on fees but on what is left after closing: VAT on remaining stock, the last ZUS contributions, company debts for which the management board is liable. Below: how to choose your route, closing a JDG step by step, liquidating a sp. z o.o. with deadlines and fees, when bankruptcy is required, and what to keep after closing. If you are a foreigner leaving Poland, the same rules apply; plan the closing before you move.
When people search for how to close a company in Poland
Usually the decision is already made: the store or service does not pay, the owner is moving abroad, taking a job or switching to another legal form. The first searches are "close business in Poland" and "how to close a company in Poland", then "suspend or close", "how much does liquidating a sp. z o.o. cost", "how long does removal from KRS take", "what about the stock in the warehouse" and "can I close a company with debts".
The last question is the most dangerous. A sp. z o.o. is liquidated when there is enough money to settle with everyone. If there is not, it cannot be closed "quietly", and delay shifts the debts onto the board members.
Which closing route fits your business
Two things set the route: the legal form, and whether the business can pay its debts.
| Situation | Procedure | Timing | Fee, PLN |
|---|---|---|---|
| JDG, you are stopping the business | Removal from CEIDG | next business day after the application | 0 |
| JDG, you want a break, not closure | Suspension in CEIDG | from 30 days, no upper limit | 0 |
| Sp. z o.o. without debts, or with debts it can pay | Liquidation through KRS | no earlier than 6 months after the notice to creditors | from 610 |
| The business has not paid its obligations for over 3 months | Bankruptcy petition | file within 30 days of insolvency | — |
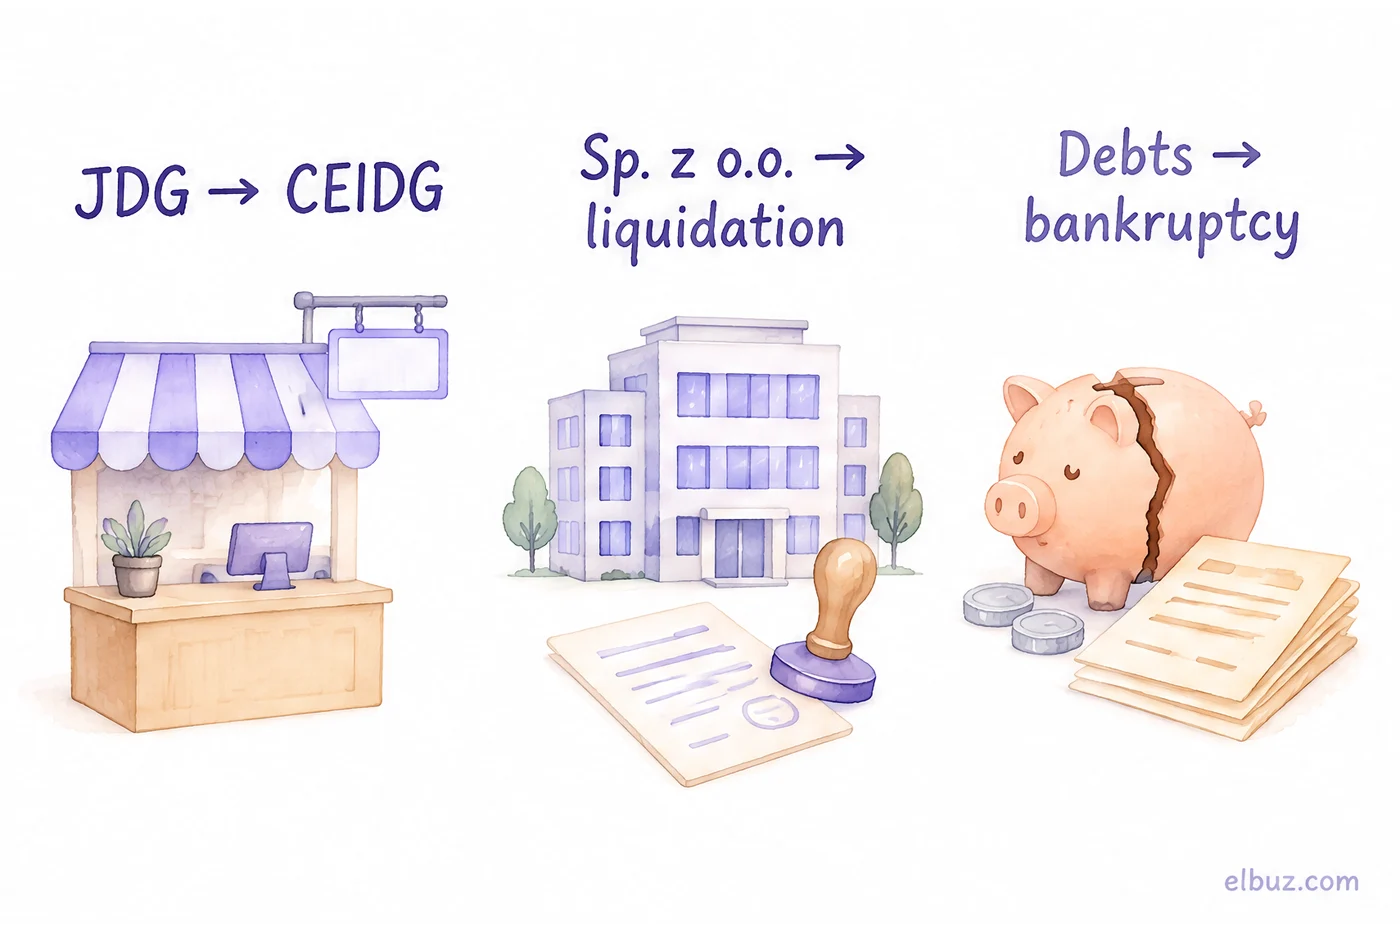
Partnerships (general, professional, limited) can be dissolved without liquidation if all partners unanimously agree how to divide the assets. A sp. z o.o. has no such shortcut: only liquidation, bankruptcy, a merger with another company or selling the shares to a new owner.
Suspend or close? If you are not sure you are stopping for good, a JDG without employees can be suspended for at least 30 days or indefinitely, and no ZUS contributions are paid during that time. Closing is better when you know you will not come back: a suspended business still appears in CEIDG and keeps some obligations towards the tax office.
How to close a JDG: five steps
Closing a JDG means an application in CEIDG plus settling with ZUS and the tax office, which the application alone does not do.
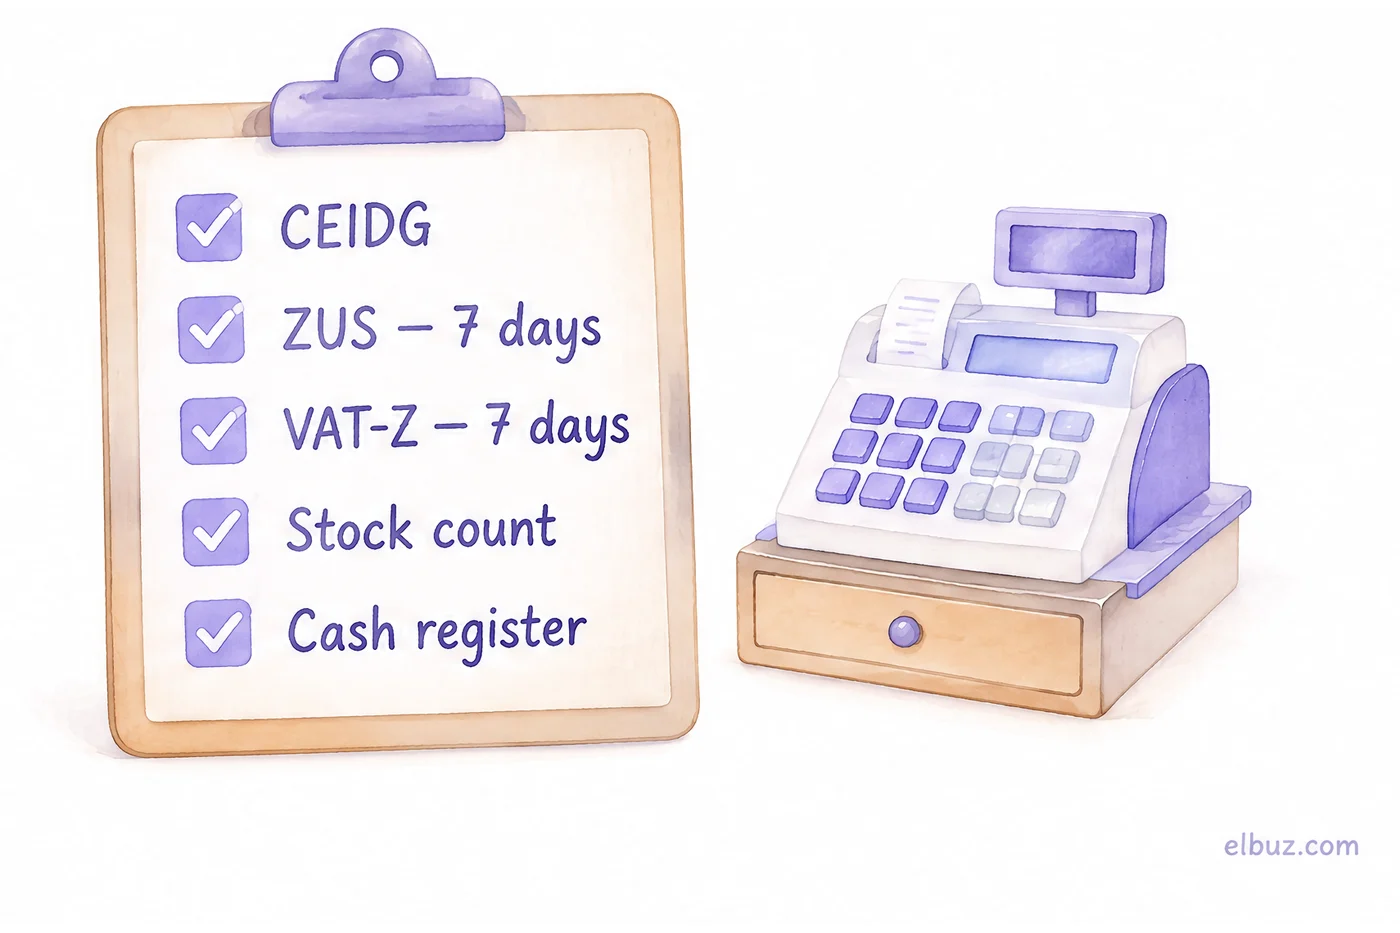
- Application for removal from CEIDG. Filed online on biznes.gov.pl, at the municipal office, or by post with a notarised signature; the application states the actual end date of the business. There is no fee. CEIDG passes the data to the tax office, Statistics Poland and ZUS.
- Deregistration from ZUS within 7 days. Within 7 days of actually ending the business, you deregister yourself, your employees and family members on forms ZUS ZWUA and ZCNA; they can be attached to the CEIDG application. Contributions for the last month are paid the following month, usually by the 20th: social contributions in proportion to the days, the health contribution in full.
- VAT-Z and stock count within 7 days. An active VAT payer files VAT-Z within 7 days of closing and draws up a stock count (spis z natury) of goods on which VAT was deducted and which remain. VAT on that remaining stock is paid in the last JPK_V7.
- Closing inventory and asset list. If you kept a revenue and expense ledger (KPiR), you draw up a stock count for income tax on the closing date and enter its value in the ledger. Everyone draws up a list of business assets: selling them within 6 years after closing may give taxable income.
- Cash register and employees. The fiscal cash register is deregistered, and employment contracts are terminated before the closing date.
What VAT on remaining stock means in numbers. Illustrative example for the arithmetic. An online store run as a JDG closes with goods worth PLN 10,000 at net purchase price left in the warehouse, all at the 23% rate. You deducted that VAT when buying, so on closing you pay it back: 10,000 × 23% = PLN 2,300 in the last JPK_V7. If you sell the stock before the closing date, those PLN 2,300 become VAT on sales paid by the buyers. If there are no goods on the closing date, the last return includes a statement that the stock count is PLN 0. VAT rates and thresholds are covered in the guide to VAT registration in Poland.
The annual income tax return for the year of closing is filed by the normal deadline. How the tax is calculated in your tax form is in the article on self-employed taxes in Poland.
Liquidating a sp. z o.o.: steps and deadlines
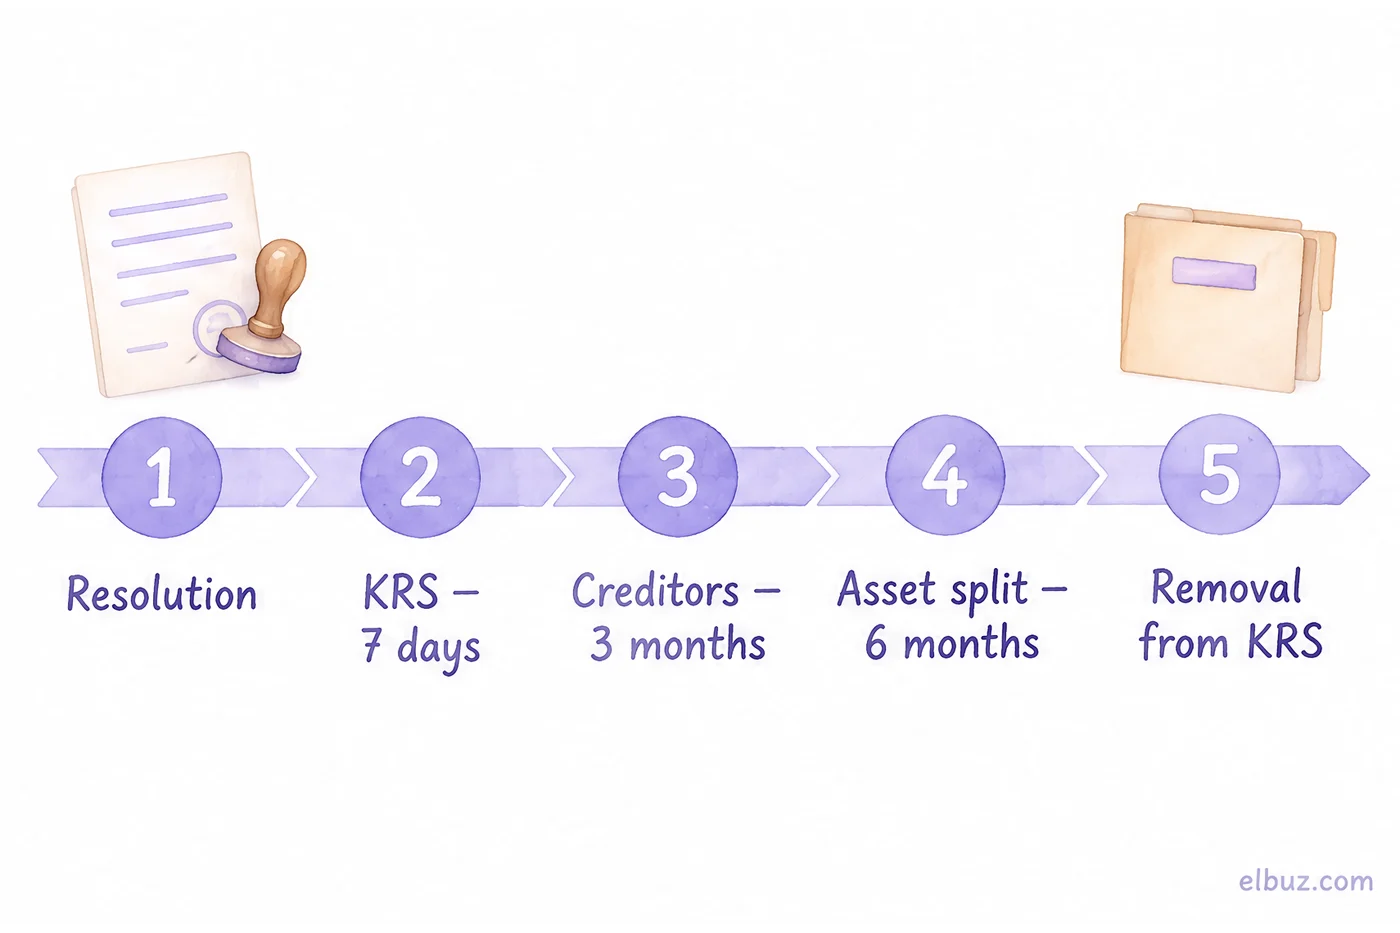
Liquidating a sp. z o.o. takes at least 6 months from the notice to creditors, because the law does not allow assets to be distributed to shareholders earlier. The order:
- Dissolution resolution. The shareholders adopt a resolution to dissolve the company and open liquidation, recorded by a notary. By default the board members become liquidators unless the resolution names others.
- Application to KRS within 7 days. Within 7 days the liquidators file an application to KRS to open liquidation: the resolution, the liquidators' consents with addresses for service, the method of representation. Electronically only: through the Court Registers Portal (PLN 250) or S24 if the company was set up there (PLN 200). "W likwidacji" (in liquidation) is added to the name; the tax office is notified on form NIP-8. Commercial power of attorney (prokura) expires when liquidation opens.
- Balance sheet and call to creditors. The liquidators draw up an opening liquidation balance sheet and publish a notice in MSiG (form MSiG-M1) calling on creditors to submit claims within 3 months. The notice costs PLN 0.70 per character, at least PLN 60.
- Liquidation work and distribution of assets. The company finishes current business, collects receivables, sells assets and settles with creditors. What is left is divided among the shareholders, no earlier than 6 months after the notice.
- Removal from KRS. The liquidators prepare a liquidation report, the shareholders approve it and name a custodian for the books and documents. The removal application costs PLN 300; it includes the report and statements that creditors have been satisfied and that there are no court, administrative or enforcement proceedings. The company ceases to exist when the removal decision becomes final.
After removal from KRS, the tax office is notified of the end of VAT activity on form VAT-Z, and the contribution payer is deregistered from ZUS. REGON is not closed separately: Statistics Poland receives the data from KRS.
Official fees for liquidating a sp. z o.o.:
| Fee | When | PLN |
|---|---|---|
| Application to open liquidation via the Court Registers Portal | within 7 days of the resolution | 250 |
| MSiG notice calling creditors | after liquidation opens | from 60 |
| Application for removal from KRS | after the liquidation report | 300 |
| Total, minimum | 610 |
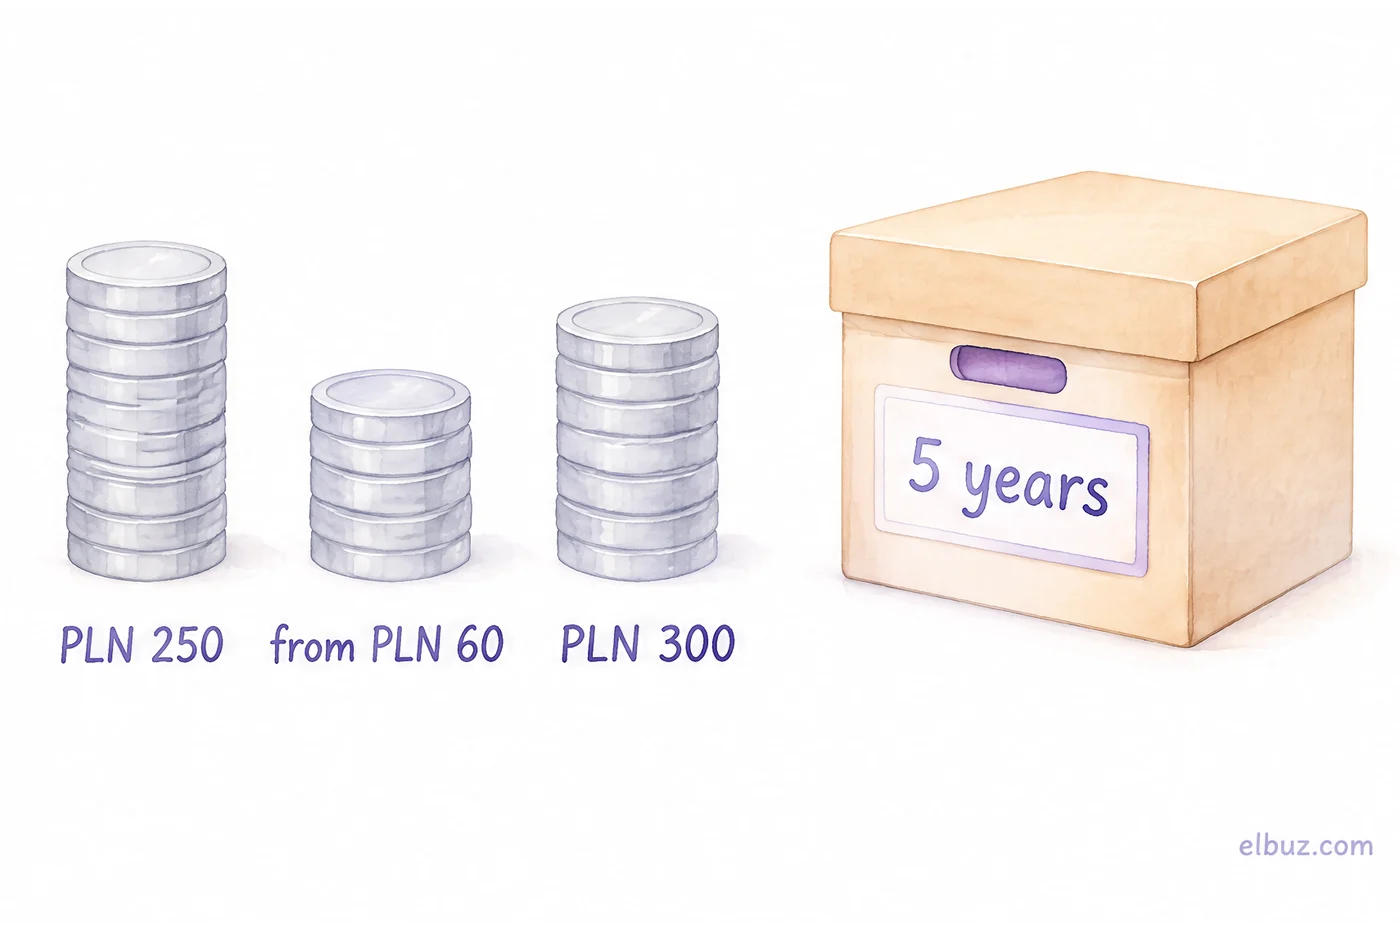
This does not include the notary's fee for recording the resolution (by their tariff) or the accountant's work on the balance sheets and report, which are usually larger items than the fees. The separate PLN 100 for an MSiG notice of the register entry has not been charged since November 29, 2025: the court publishes entries itself.
When bankruptcy is required instead of liquidation
Bankruptcy is required when the business is insolvent: under Polish law that is the case when payment of monetary obligations is more than 3 months overdue. From that moment the debtor has 30 days to file for bankruptcy. Since December 2021 petitions are filed only electronically, through the National Register of Debtors (KRZ).
For a sp. z o.o. this deadline matters personally to the board. If enforcement against the company proves ineffective, the board members are jointly liable for its obligations with their own assets (Article 299 of the Commercial Companies Code). Filing for bankruptcy in time is one of the things that releases them. That is why a liquidation with debts that cannot be covered is not "carried to the end": the liquidator also has to file.
If the business is still viable and the problem is a temporary lack of cash, there is restructuring under the Restructuring Law: an arrangement with creditors to spread out or write off part of the debt so the business keeps running. Bankruptcy and restructuring go through the court and require a lawyer or a restructuring adviser: this article explains when to go to them, not how to run the procedure yourself.
Closing a JDG does not close its debts: the owner is liable for business obligations with all personal assets, and removal from CEIDG does not cancel them. Tax arrears remain together with interest; how it is calculated is in the article on penalties for unpaid taxes in Poland.
What to keep after closing
Tax documents are kept for 5 years from the end of the year in which the tax payment deadline passed: the KPiR ledger, VAT records, returns, the stock count. ZUS documents usually for 5 years from filing; employee records for 10 or 50 years depending on when the employee was hired. In a sp. z o.o., the books go to the custodian named by the shareholders after liquidation.
An online store should add exports of orders, invoices and customer correspondence to this list: the tax office may check turnover, and customers may return goods or file complaints after you close. Export them from your store platform and marketplaces before you close the accounts.
Common mistakes when closing a business
- Closing a JDG with a full warehouse. VAT on the remaining stock has to be paid out of your own pocket. Selling it off before the closing date or returning it to the supplier is cheaper.
- Assuming CEIDG "closed everything". The application passes data to ZUS and the tax office, but contributions for the last month, VAT-Z and the stock count are your job, and late payments accrue interest.
- Opening liquidation of an indebted sp. z o.o. Liquidation does not cancel debts, the 30-day bankruptcy deadline runs out meanwhile, and liability passes to the board.
- Distributing assets before 6 months. The Commercial Companies Code forbids it: until the deadline passes, a creditor may come forward, and the money for that claim must stay in the company.
- Throwing away documents after closing. The tax office can audit for 5 years, and without documents you cannot prove your costs.
Frequently asked questions
How do I close a sole proprietorship in Poland online?
File an application for removal from CEIDG on biznes.gov.pl with the end date of the business; it is free, and the entry disappears the next business day. Within 7 days deregister from ZUS, and an active VAT payer files VAT-Z.
Can I just shut down my company in Poland?
A JDG, almost: removal from CEIDG takes effect the next business day, though ZUS and VAT settlements take up to 7 more days. A sp. z o.o. cannot be closed that fast; liquidation takes at least 6 months.
How much does it cost to liquidate a sp. z o.o.?
Official fees start at PLN 610: PLN 250 for the KRS application, from PLN 60 for the MSiG notice and PLN 300 for removal. The notary's fee for the resolution and the accountant's work on balance sheets and the report are paid separately.
Can I close a company with debts in Poland?
Through liquidation, only if the debts can be paid. When a business has not paid its obligations for over 3 months, a bankruptcy petition is filed within 30 days; delay risks personal liability of the board under Article 299 of the Commercial Companies Code.
Do I have to pay taxes when I close my business?
Yes. VAT on remaining stock goes in the last JPK_V7, contributions for the last month are paid the following month, and the annual income tax return for the year of closing is filed by the normal deadline.
Is it better to suspend or close a business?
Suspend if you plan to come back: a JDG without employees is suspended for at least 30 days or indefinitely, with no ZUS contributions. Close if you are stopping for good and want no further business obligations.
Sources
- How to end a sole proprietorship — biznes.gov.pl; suspending or closing a business (in English) — biznes.gov.pl/en.
- How to dissolve a company and remove it from KRS (KRS and MSiG fees, change from November 29, 2025) — biznes.gov.pl.
- Suspending a business in CEIDG — biznes.gov.pl.
- Ending a business: tax obligations — podatki.gov.pl.
- Commercial Companies Code, Arts. 270–290 (dissolution and liquidation of a sp. z o.o.), Art. 299 (board liability) — isap.sejm.gov.pl.
- Bankruptcy Law, Arts. 11 and 21 (insolvency, 30 days to file) — isap.sejm.gov.pl.
Checked on October 31, 2026. The stock VAT example is illustrative.


