

Estonian CIT (estoński CIT) is a Polish regime in which a company pays corporate tax only when it distributes profit to its owners. The rate is 10% for a small taxpayer or a new company and 20% for the rest; the owner's dividend tax is then reduced by 90% or 70% of the company's tax. In total that is 20% or 25%, against 26.29% or 34.39% under standard CIT. It is open to companies owned only by individuals.
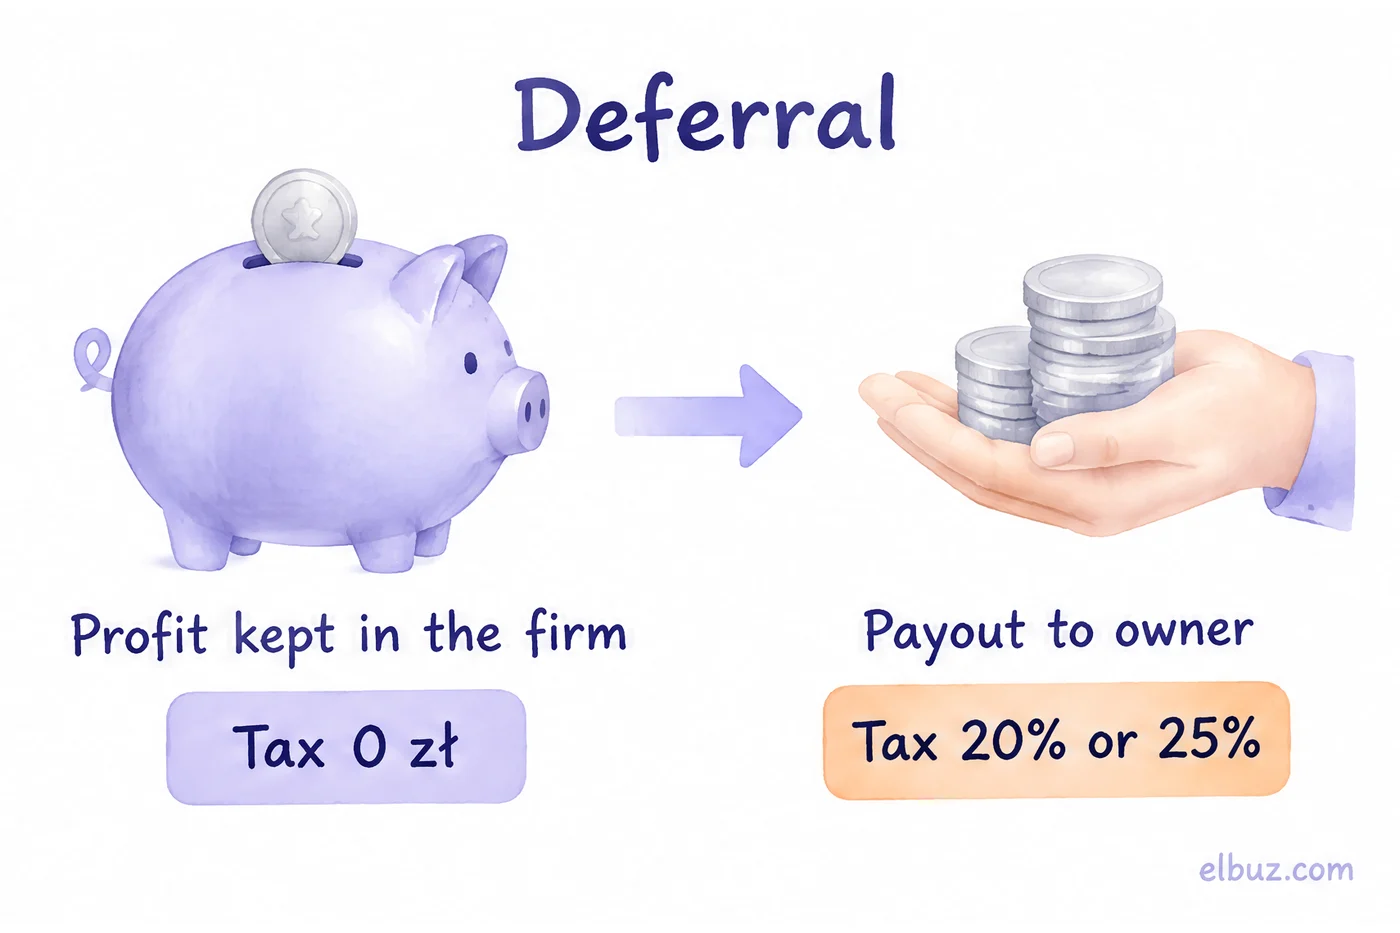
Judging the regime by the rate alone misses the point: the real benefit is deferral. While profit stays in the company and goes into stock or growth, no tax is due at all. Companies lose the benefit on details: a loan to the owner, private expenses paid from the company account, a missed employment condition. Below: the conditions, an illustrative calculation and the most common mistakes.
When people search for Estonian CIT
Typically the owner of a sp. z o.o., or of a growing sole proprietorship, hears from an accountant: "switch to Estonian CIT and pay less". They search for "Estonian CIT Poland" and then ask: what are the conditions, what are the rates, can I switch mid-year, does it work for a new company?
"How much lower is the rate" is not the key question. What matters more is whether you plan to keep profit in the company: if you take it all out every month anyway, the gain is smaller and the restrictions remain.
Who can switch to Estonian CIT
All conditions must be met together and for as long as you use the regime.
- Legal form. Sp. z o.o., joint-stock company, simple joint-stock company, limited partnership or limited joint-stock partnership. A sole proprietorship (JDG) cannot use it and has to convert first, see converting a JDG into a sp. z o.o..
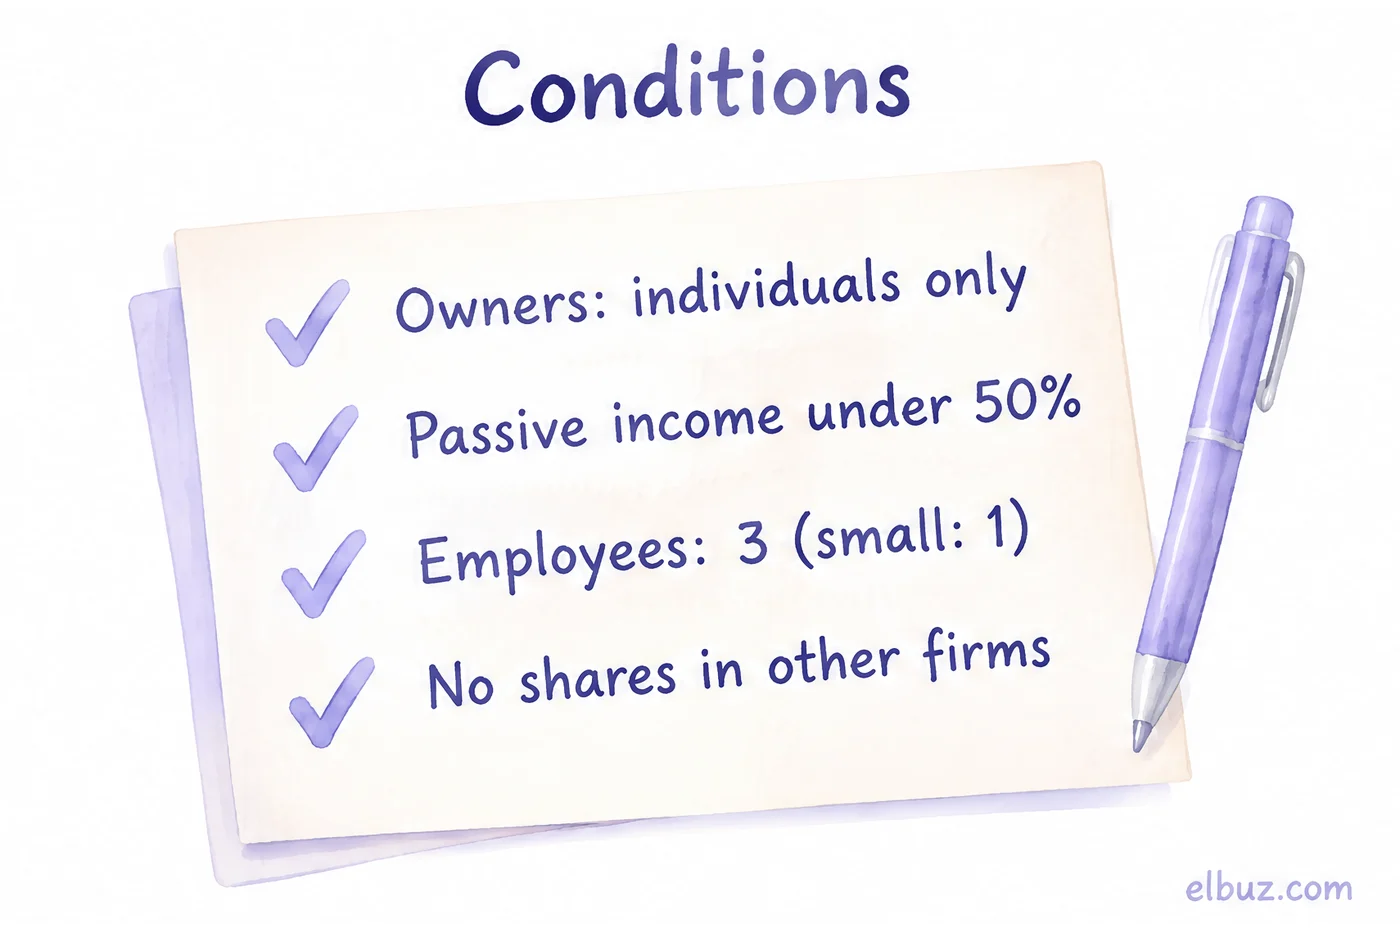
- Owners are individuals only. A company with another company among its shareholders does not qualify.
- Passive income below 50%. Interest, loans, leasing, royalties, sales of financial instruments and transactions with related parties must stay under half of revenue.
- Employees. At least 3 people on employment contracts for over 300 days a year (1 for a small taxpayer), or other contracts costing at least 3 average monthly salaries (1 for a small taxpayer) with ZUS and PIT withheld. A new company is exempt in its first year and the next 2 years, but from the second year must add at least one full-time job each year.
- No shares in other companies or investment funds, and no IFRS financial statements.
Banks, lending institutions, companies in special economic zones, companies in liquidation or bankruptcy and companies formed by merger or division cannot use the regime.
The rates and how they work with dividends
The company rate is 10% for a small taxpayer (sales including VAT in the previous year up to 8,517,000 zł for 2026) and in the first year of business, 20% for others. The owner pays 19% PIT on the dividend but deducts 90% (small taxpayer) or 70% (others) of the tax the company paid.
Calculation: Estonian CIT vs standard CIT
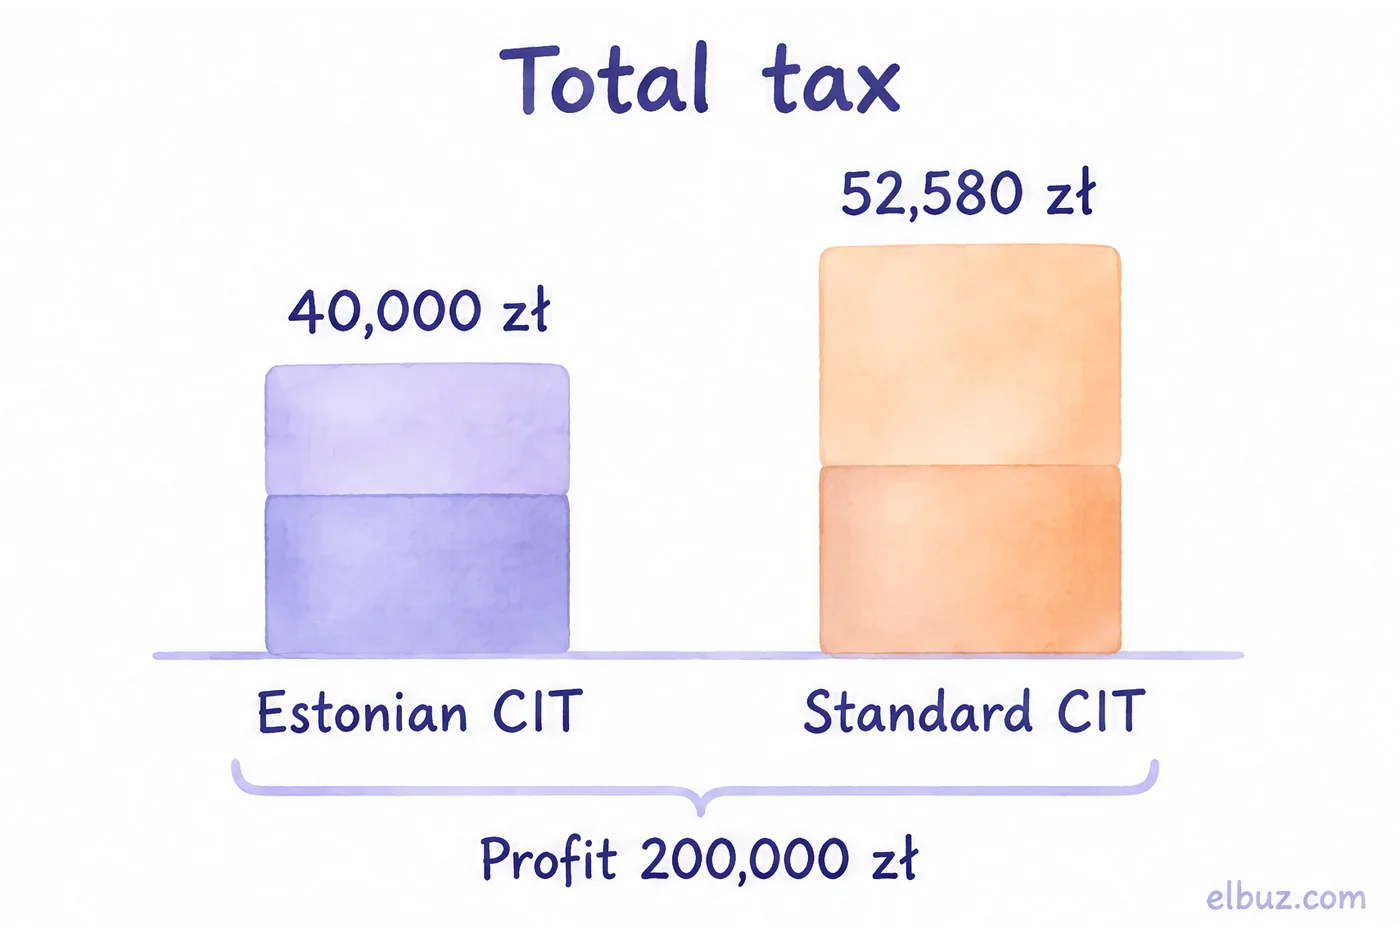
An illustrative example for the arithmetic, not market data: a company earns 200,000 zł of profit and pays all of it to its individual owner. Rates are taken from podatki.gov.pl and biznes.gov.pl.
| Option | Company tax, zł | Dividend tax, zł | Total, zł | Total rate |
|---|---|---|---|---|
| Estonian CIT, small taxpayer | 20,000 | 20,000 | 40,000 | 20% |
| Standard CIT 9%, small taxpayer | 18,000 | 34,580 | 52,580 | 26.29% |
| Estonian CIT, others | 40,000 | 10,000 | 50,000 | 25% |
| Standard CIT 19%, others | 38,000 | 30,780 | 68,780 | 34.39% |
How the first row works: 10% of 200,000 is 20,000 zł of company tax; the 19% dividend tax is 38,000 zł, minus 90% of the 20,000 already paid, i.e. 18,000; 20,000 zł remains. Under standard CIT the company pays 18,000 zł, the owner receives 182,000 zł and pays 19% of it, 34,580 zł.
The 12,580 zł difference only appears when profit is paid out. If the 200,000 zł stays in the company to buy stock, Estonian CIT is zero, while standard CIT still takes 18,000 zł in advances during the year.
How to switch: deadlines and forms
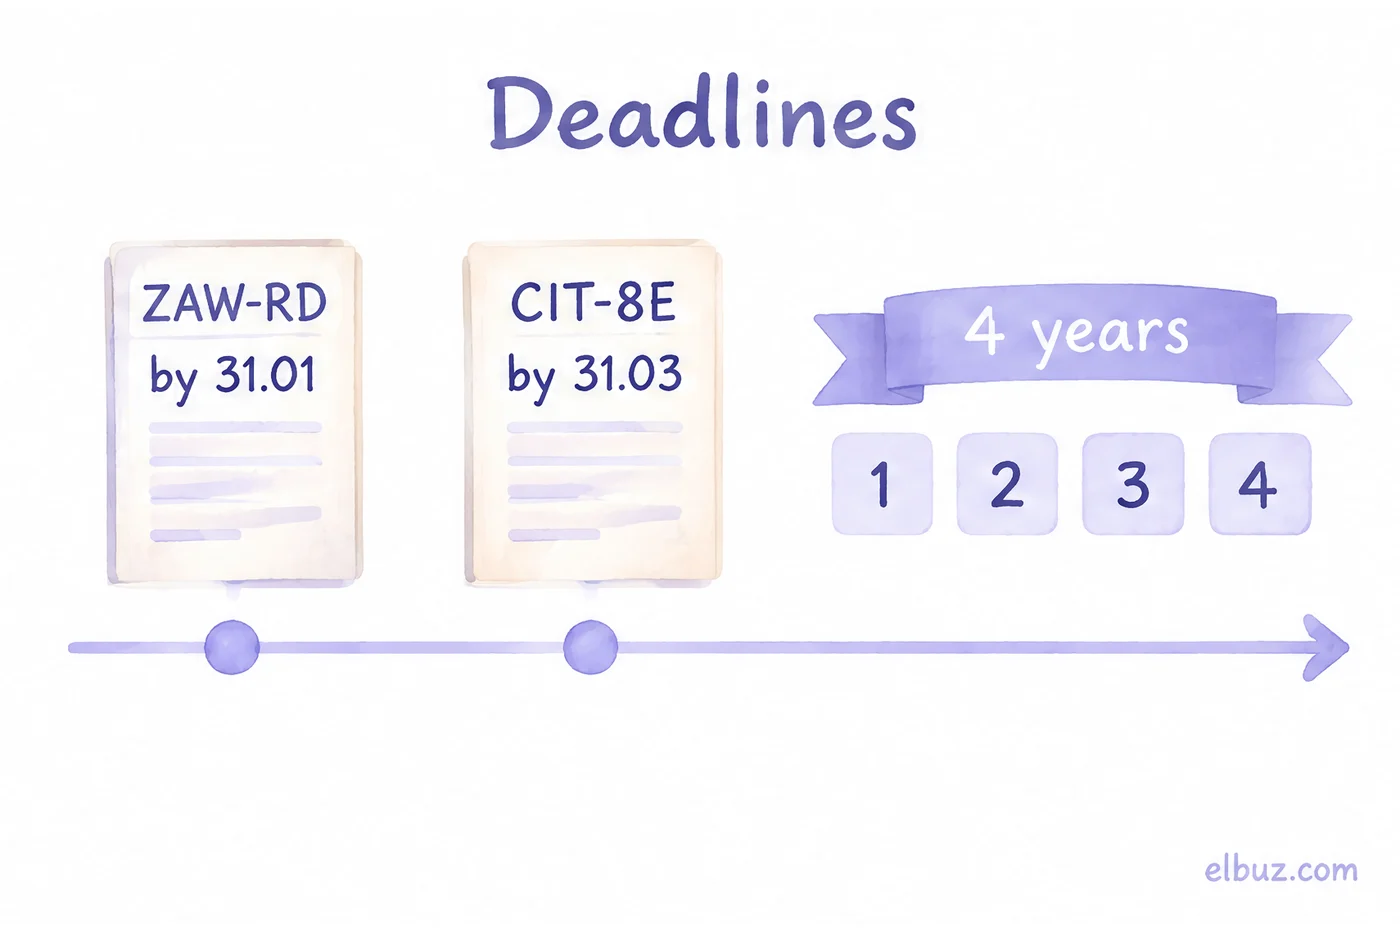
- ZAW-RD notice to the tax office by the end of the first month of the tax year you start with (31 January for a calendar year). You can switch mid-year, but then you must close the books and prepare financial statements under standard CIT.
- Four years. The regime is chosen for 4 consecutive years and renews automatically for another 4 unless you opt out.
- CIT-8E return every year by the end of the third month after the tax year, filed electronically. It is informational: tax on distributed profit is due by the end of the third month of the year after the year in which the distribution was resolved.
Where companies lose the benefit
- Hidden profits (ukryte zyski). A loan from the company to the owner, paying the owner's private costs, free use of company assets: all of it is taxed as a profit distribution in the month it happens.
- Non-business expenses are taxed immediately, in the month of the expense.
- Losing track of a condition. Break any condition and you lose the regime; you can only choose it again 36 months after the year you lost it.
- Expecting it for a JDG. Sole proprietors cannot use it; compare JDG tax forms separately in taxes for a sole trader in Poland.
- Forgetting the 4-year cycle. The regime renews itself; to opt out, you state it in the return filed by the end of the third month after the year.
Before you decide, know what it takes to close a company if the business does not work out; it is more involved than closing a JDG: how to close a business in Poland.
Frequently asked questions
What is Estonian CIT in simple terms?
A regime in which a company pays corporate tax only when it distributes profit to its owners. While profit stays in the company, no tax is due.
What are the Estonian CIT rates in 2026?
10% for a small taxpayer and in the first year, 20% for others. Together with the owner's dividend tax, the total is 20% or 25%.
Can a sole proprietorship use Estonian CIT?
No. Only companies qualify: sp. z o.o., joint-stock, simple joint-stock and limited partnerships. A JDG has to convert into a company first.
Can a new company choose Estonian CIT straight away?
Yes. In the first year the income-structure condition is treated as met, and the employment condition does not apply in the first year and the next 2 years.
When is the ZAW-RD notice due?
By the end of the first month of the tax year in which the regime starts. For a calendar year, by 31 January.
What are hidden profits under Estonian CIT?
Any benefit to the owner instead of a dividend: a loan, paying private costs, free use of assets. They are taxed like a profit distribution.
Sources
- Biznes.gov.pl, Estoński CIT (conditions, calculation examples, deadlines, hidden profits) — 001171.
- Podatki.gov.pl, Estonian CIT rates and limits (10% and 20%, small taxpayer limit 8,517,000 zł for 2026) — podatki.gov.pl.
- Podatki.gov.pl, Estonian CIT basics (ZAW-RD, 36 months before choosing again) — podatki.gov.pl.
Checked 31.10.2026.


